Maximize Your Retirement: Navigating 2026 401(k) and 403(b) Contribution Limits
Planning for retirement is a cornerstone of financial stability, and understanding the nuances of employer-sponsored retirement plans like 401(k)s and 403(b)s is paramount. As we look ahead to 2026, anticipating the updated contribution limits for these accounts becomes a critical step in optimizing your savings strategy. While the official figures for 2026 are typically released by the IRS in late fall of the preceding year, we can make informed projections based on historical trends and economic indicators. This comprehensive guide will delve into the anticipated 2026 retirement limits for 401(k)s and 403(b)s, explore the benefits of maximizing your contributions, and provide actionable strategies to help you achieve a robust and secure retirement.
Anúncios
Understanding 401(k) and 403(b) Plans
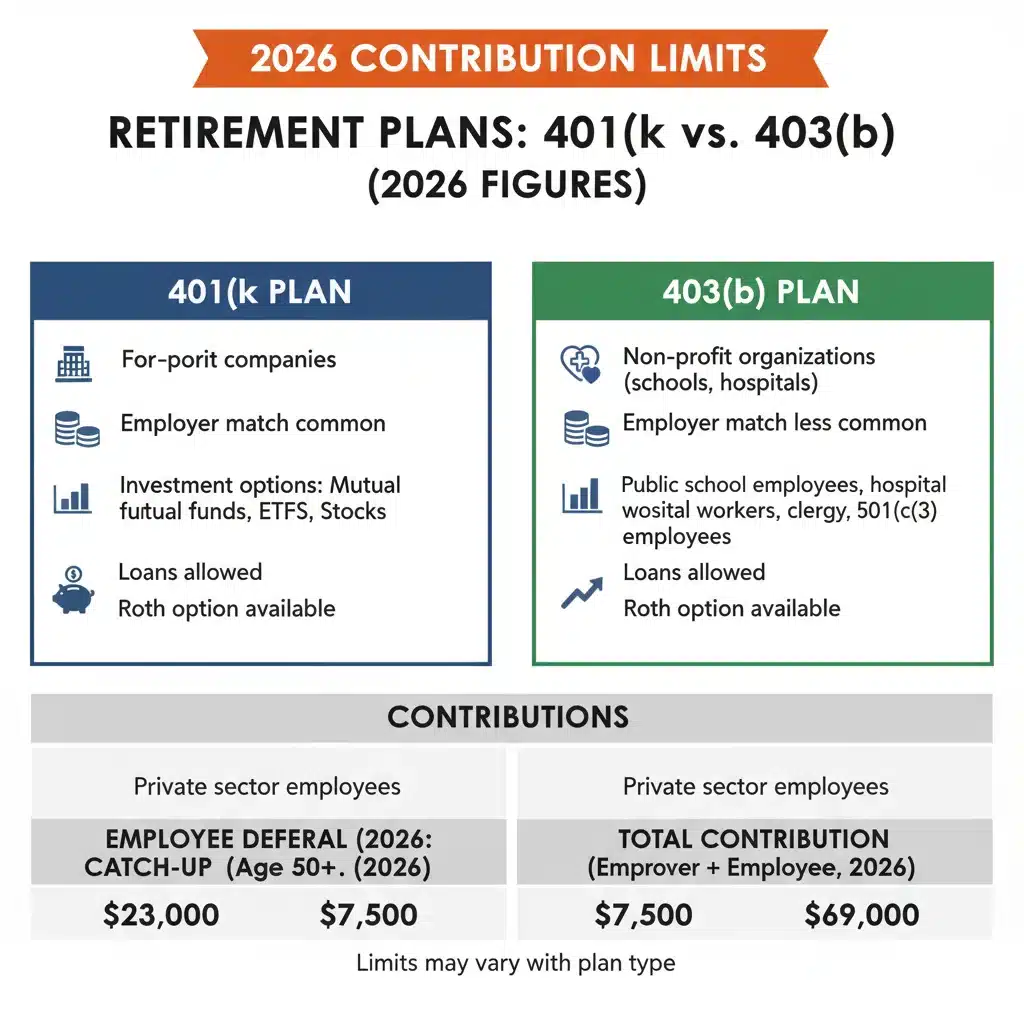
Before diving into the specifics of the 2026 retirement limits, let’s briefly review the fundamentals of 401(k) and 403(b) plans. Both are employer-sponsored defined contribution plans designed to help employees save for retirement on a tax-advantaged basis. The primary difference lies in the type of employer offering them.
- 401(k) Plans: These are typically offered by for-profit companies. Contributions are often pre-tax, meaning they reduce your taxable income in the year they are made. Earnings grow tax-deferred until retirement, at which point withdrawals are taxed as ordinary income. Many employers also offer a Roth 401(k) option, where contributions are made with after-tax dollars, and qualified withdrawals in retirement are tax-free.
- 403(b) Plans: These plans are generally available to employees of public schools, colleges, universities, hospitals, and certain other tax-exempt organizations (501(c)(3) organizations). Like 401(k)s, they typically allow for pre-tax contributions and tax-deferred growth, with Roth 403(b) options also becoming more common.
Both plan types share the common goal of encouraging long-term savings, often supplemented by employer matching contributions, which are essentially free money for your retirement. Understanding the mechanics of these plans is the first step toward effectively utilizing the 2026 retirement limits to your advantage.
Anúncios
Projected 2026 Retirement Contribution Limits
The IRS typically adjusts contribution limits annually to account for inflation, using a specific formula. While the official numbers for 2026 are not yet released, we can make educated guesses based on recent inflation rates and historical adjustments. For context, in 2024, the 401(k) and 403(b) contribution limit for employees was $23,000, with an additional $7,500 catch-up contribution for those aged 50 and over. Given ongoing inflationary pressures and economic growth, it is reasonable to anticipate an increase for 2026.
Anticipated Employee Contribution Limits for 2026
Based on current projections and historical data, the employee contribution limit for 401(k) and 403(b) plans in 2026 is likely to see a modest increase. We could see this limit rise to approximately $24,000 to $25,000. This increase, though seemingly small year-over-year, can significantly impact your retirement nest egg over decades of saving. It’s crucial for individuals to monitor these announcements closely as the year progresses.
Anticipated Catch-Up Contribution Limits for 2026
For those aged 50 and older, the IRS allows for additional "catch-up" contributions to help accelerate retirement savings. This provision acknowledges that older workers may have less time to save and might be in a better financial position to contribute more. The catch-up contribution limit for 401(k) and 403(b) plans is also subject to annual adjustment. For 2026, we might see this limit increase slightly from its current $7,500, potentially reaching around $8,000. If you are approaching or are already over 50, maximizing these catch-up contributions is an incredibly powerful strategy to boost your retirement savings.
Total Contribution Limits for 2026 (Employer + Employee)
Beyond individual contributions, there’s also a total limit on contributions to a 401(k) or 403(b) from all sources – meaning your contributions, your employer’s matching contributions, and any profit-sharing contributions. This limit is significantly higher. For 2024, this total limit was $69,000 (or $76,500 for those 50 and over, including catch-up contributions). For 2026, we can expect this overall limit to also increase, potentially reaching $71,000 to $73,000, or even higher when including catch-up contributions. While most individuals won’t reach this higher threshold solely through personal contributions, it’s relevant for those with generous employer plans or who participate in mega back-door Roth strategies.
Why Maximizing Your Contributions Matters
Understanding the 2026 retirement limits is one thing; acting on them is another. Maximizing your contributions to your 401(k) or 403(b) offers several compelling benefits:
- Tax Advantages: Pre-tax contributions reduce your current taxable income, leading to immediate tax savings. Roth contributions, while not offering an upfront deduction, provide tax-free withdrawals in retirement, which can be immensely valuable, especially if you expect to be in a higher tax bracket later in life.
- Compound Growth: The earlier and more you contribute, the more time your investments have to grow through the power of compounding. Even small increases in annual contributions can lead to significantly larger balances over decades.
- Employer Match: Many employers offer a matching contribution, often 50 cents or a dollar for every dollar you contribute, up to a certain percentage of your salary. Failing to contribute enough to get the full match is like leaving free money on the table – a critical mistake in retirement planning.
- Forced Savings: Payroll deductions make saving automatic and consistent, reducing the temptation to spend money that could otherwise be allocated to your future.
- Financial Security: A larger retirement fund provides greater financial independence and peace of mind in your later years, allowing you to maintain your desired lifestyle without financial stress.
Strategies to Maximize Your 2026 Retirement Limits
With the projected 2026 retirement limits in mind, here are actionable strategies to help you make the most of your employer-sponsored retirement plans:
1. "Set It and Forget It" – Automate Your Contributions
The easiest way to ensure you’re maximizing your contributions is to automate them through payroll deductions. Review your current contribution percentage and, if possible, increase it, especially if you get a raise or bonus. Aim to contribute at least enough to get the full employer match. Beyond that, strive to reach the maximum employee contribution limit. Even a 1% or 2% increase each year can make a substantial difference over time.
2. Prioritize Catch-Up Contributions (Age 50+)
If you are 50 or older, make every effort to utilize the catch-up contribution provision. This additional contribution amount is specifically designed to help you bridge any savings gaps or simply accelerate your progress toward your retirement goals. It’s a powerful tool that should not be overlooked.
3. Understand Your Employer Match
Know the specifics of your employer’s matching contribution policy. Some companies match dollar-for-dollar up to a certain percentage, while others offer 50 cents on the dollar. Make sure you contribute at least the amount required to receive the maximum employer match. This is guaranteed return on your investment that you won’t find anywhere else.
4. Consider a Roth 401(k) or Roth 403(b)
If your employer offers a Roth option, consider diversifying your tax strategy. While traditional pre-tax contributions reduce your current taxable income, Roth contributions grow tax-free and are withdrawn tax-free in retirement. This can be particularly beneficial if you expect to be in a higher tax bracket in retirement or if you want to create a stream of tax-free income in your golden years. A balanced approach, with both pre-tax and Roth accounts, can offer flexibility.
5. Leverage "Mega Backdoor" Roth (If Available)
For high-income earners who have already maxed out their traditional and Roth 401(k)/403(b) contributions (and potentially even their IRA contributions), some plans allow for "after-tax" non-Roth contributions. These can then be converted into a Roth IRA or Roth 401(k)/403(b) through a process known as the "mega backdoor" Roth. This strategy allows you to contribute significantly more to a Roth account beyond the standard employee limits, up to the total contribution limit (employer + employee). Check with your plan administrator and a financial advisor to see if your plan allows this and if it’s appropriate for your situation.
6. Review and Adjust Annually
Don’t just set your contributions once and forget about them forever. Make it a habit to review your retirement savings strategy annually, especially when new contribution limits are announced. Assess your financial situation, adjust your contributions as needed, and ensure your investment allocations are still aligned with your risk tolerance and time horizon. The announcement of the 2026 retirement limits is a perfect trigger for this annual review.
7. Diversify Your Retirement Portfolio
While maximizing contributions is crucial, it’s equally important to ensure your investments within your 401(k) or 403(b) are appropriately diversified. Review the fund options available in your plan and ensure your asset allocation aligns with your retirement timeline and risk profile. Don’t be afraid to seek professional financial advice if you’re unsure about your investment choices.
Integrating 401(k)/403(b) with Other Retirement Accounts
While employer-sponsored plans are powerful tools, they are often just one piece of a comprehensive retirement puzzle. Consider how your 401(k) or 403(b) fits with other retirement savings vehicles:
- Individual Retirement Accounts (IRAs): Traditional and Roth IRAs offer additional ways to save, each with its own tax advantages and contribution limits. For 2026, IRA limits are also expected to see an adjustment. Contributing to an IRA can be a great way to supplement your employer plan, especially if you’ve already maxed out your 401(k)/403(b) or if your employer doesn’t offer a match.
- Health Savings Accounts (HSAs): If you have a high-deductible health plan (HDHP), an HSA can be a triple-tax-advantaged savings vehicle. Contributions are tax-deductible, earnings grow tax-free, and qualified withdrawals for medical expenses are tax-free. Many treat HSAs as a supplemental retirement account, paying for current medical expenses out-of-pocket and allowing the HSA funds to grow for retirement.
- Taxable Brokerage Accounts: For those who have maxed out all tax-advantaged accounts, a taxable brokerage account can provide additional investment opportunities. While not offering the same tax benefits, they provide liquidity and flexibility.
A holistic approach to retirement planning ensures you are leveraging all available tools to build a robust financial future.
Impact of Inflation and Economic Factors on 2026 Limits
The annual adjustments to retirement contribution limits are primarily driven by inflation. The IRS uses specific cost-of-living adjustments (COLAs) to determine these changes. Strong inflation, as we’ve seen in recent years, tends to push these limits higher. Conversely, periods of low inflation might result in smaller, or even no, increases. Economic growth, wage growth, and overall market performance also play indirect roles by influencing the calculations that lead to these adjustments.
While our projections for the 2026 retirement limits are based on current trends, it’s important to remember that economic conditions can shift. Staying informed about economic forecasts and IRS announcements will be key to precise planning. Financial advisors often have access to more detailed projections and can help you model various scenarios for your retirement savings.
Common Mistakes to Avoid
Even with the best intentions, some common pitfalls can hinder your retirement savings efforts:
- Not Contributing Enough to Get the Full Match: As reiterated, this is free money. Don’t miss out.
- Ignoring Catch-Up Contributions: If you’re 50 or over, these additional contributions are a goldmine for boosting your savings.
- Being Too Conservative: Especially for younger savers, being overly cautious with investments can mean missing out on significant growth potential. A diversified portfolio aligned with your risk tolerance is crucial.
- Frequent Trading: Constantly buying and selling within your retirement account can lead to higher fees and potentially lower returns. A long-term, buy-and-hold strategy often proves more effective.
- Not Reviewing Beneficiaries: Life changes. Ensure your beneficiaries are up-to-date on all your retirement accounts.
- Taking Early Withdrawals: Withdrawing funds before retirement age (typically 59½) can incur significant penalties and taxes, severely undermining your long-term goals. Avoid this at all costs unless absolutely necessary.
- Failing to Plan for Taxes in Retirement: Understanding the tax implications of your withdrawals (pre-tax vs. Roth) is vital. A diversified tax strategy can provide flexibility in retirement.
Conclusion: Proactive Planning for 2026 and Beyond
The anticipated 2026 retirement limits for 401(k) and 403(b) plans offer a fresh opportunity to evaluate and enhance your retirement savings strategy. By staying informed about these limits, understanding the various contribution options, and implementing smart saving strategies, you can significantly impact your financial future. Whether you’re just starting your career or nearing retirement, maximizing these tax-advantaged accounts is a cornerstone of a secure and comfortable retirement.
Remember to consult with your plan administrator and a qualified financial advisor for personalized advice tailored to your specific situation. Proactive planning today will pave the way for a more prosperous tomorrow. Don’t wait for the official announcements; start strategizing now to make 2026 your best retirement savings year yet!