Maximize Your Health Savings Account (HSA) in 2026: New Contribution Limits and Investment Strategies
Are you ready to take control of your healthcare costs and supercharge your long-term savings? The Health Savings Account (HSA) remains one of the most powerful financial tools available, offering a unique triple-tax advantage that savvy individuals leverage for both immediate medical expenses and future retirement planning. As we look ahead to 2026, understanding the updated contribution limits and refining your investment strategies will be paramount to fully capitalizing on this incredible benefit. This comprehensive guide will delve into everything you need to know to maximize your HSA in 2026, ensuring you’re well-prepared for any health-related financial challenges that may arise.
Anúncios
For many, healthcare expenses are an unavoidable reality. From routine check-ups to unexpected emergencies, these costs can quickly add up. This is where the HSA shines, providing a tax-advantaged way to save and pay for qualified medical expenses. But an HSA is much more than just a savings account for healthcare; it’s a versatile investment vehicle that can significantly boost your retirement nest egg. Let’s explore how to make the most of your HSA in 2026.
Understanding the HSA Basics and Eligibility for 2026
Before diving into advanced strategies, it’s crucial to grasp the fundamental principles of an HSA and determine your eligibility for 2026. An HSA is a tax-advantaged savings account that can be used for qualified medical expenses. To be eligible to contribute to an HSA, you must be covered by a High Deductible Health Plan (HDHP) and not be enrolled in Medicare, nor be claimed as a dependent on someone else’s tax return. The IRS defines an HDHP as a health plan with a minimum annual deductible and a maximum annual out-of-pocket expense.
Anúncios
The beauty of an HSA lies in its triple-tax advantage:
- Tax-Deductible Contributions: Contributions you make to your HSA are tax-deductible, reducing your taxable income in the year they are made.
- Tax-Free Growth: Any investment earnings within your HSA grow tax-free. This means no capital gains taxes or dividend taxes as long as the funds remain in the account.
- Tax-Free Withdrawals: Withdrawals for qualified medical expenses are completely tax-free. This is where the HSA truly stands out, offering a benefit unparalleled by other retirement accounts like 401(k)s or IRAs for healthcare costs.
It’s important to note that if you withdraw funds for non-qualified expenses before age 65, the withdrawals are subject to your ordinary income tax rate plus a 20% penalty. After age 65, non-qualified withdrawals are taxed at your ordinary income tax rate, similar to a traditional IRA.
Anticipated HSA Contribution Limits for 2026
One of the most anticipated updates each year pertains to the HSA contribution limits. While the official numbers for 2026 are typically released by the IRS later in the year, we can project based on historical trends and inflation adjustments. These limits dictate the maximum amount you can contribute to your HSA annually, and understanding them is key to maximizing your HSA in 2026.
For reference, let’s consider the 2025 limits (which are usually announced in May-June of the preceding year, e.g., 2025 limits announced in May-June 2024). Typically, these limits see a modest increase year over year due to inflation. For 2025, the projected limits are often:
- Self-Only Coverage: Approximately $4,150 – $4,200
- Family Coverage: Approximately $8,300 – $8,400
- Catch-up Contribution (Age 55 and older): An additional $1,000 (this amount has historically remained constant)
Based on these trends, we can anticipate a slight increase for 2026. It is crucial to check the official IRS announcements as soon as they become available to get the precise figures. Always aim to contribute the maximum allowable amount if your financial situation permits. This strategy allows you to take full advantage of the tax deductions and gives your investments more capital to grow over time, significantly helping you maximize your HSA in 2026.
Strategic Investment Approaches for Your HSA in 2026
Simply contributing to an HSA is a good start, but the real power comes from investing those funds. Unlike a typical checking or savings account, many HSAs offer investment options, allowing your money to grow tax-free over the long term. This is a critical component of how to maximize your HSA in 2026. Think of your HSA as a stealth retirement account specifically for healthcare expenses.
1. Early Investment for Compounding Growth
The sooner you start investing your HSA funds, the more time compounding interest has to work its magic. Even if you’re relatively young and healthy, consider paying for current medical expenses out-of-pocket (if feasible) and letting your HSA contributions grow untouched. This allows you to preserve your HSA balance for significant future medical costs, potentially in retirement, when healthcare expenses tend to be higher.
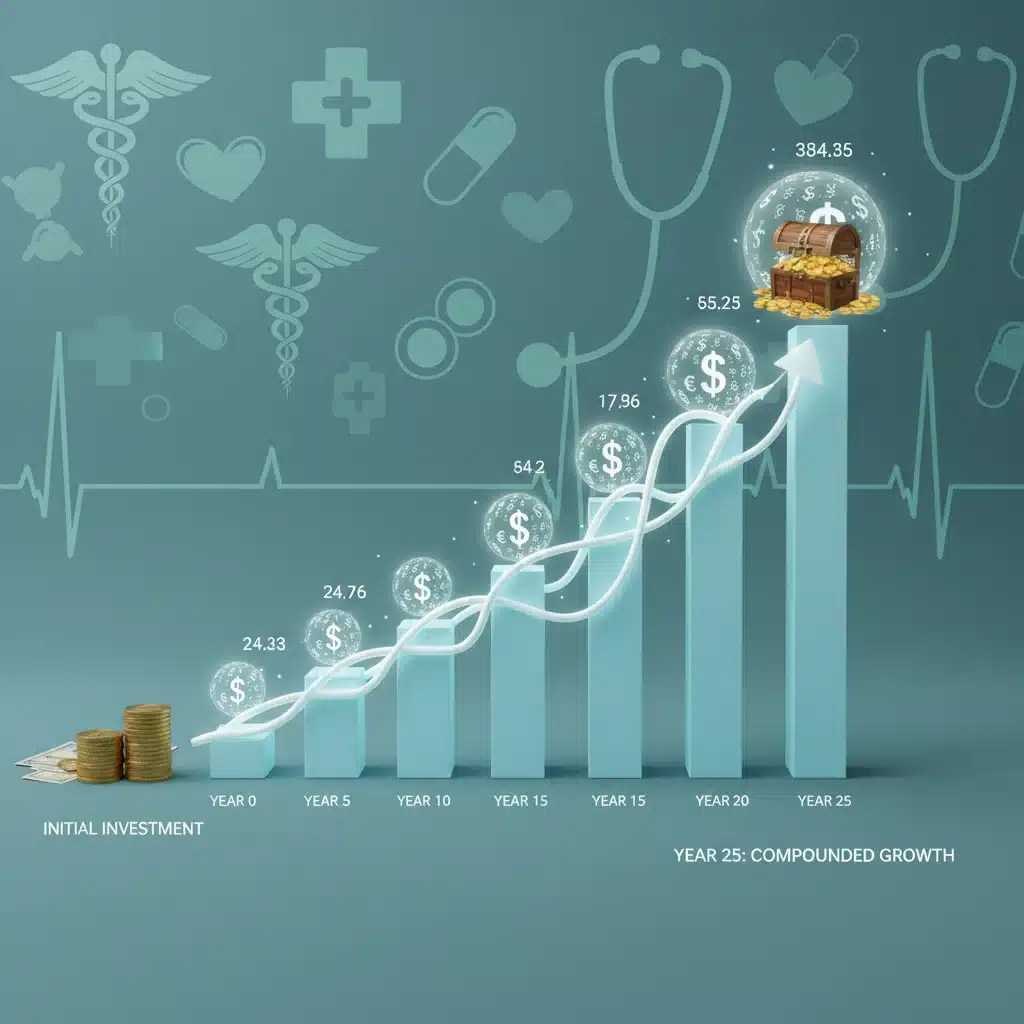
Imagine contributing the maximum family coverage amount for 20-30 years and letting it grow at an average annual return of 7%. The potential for a substantial tax-free nest egg is enormous. This long-term perspective is vital for those looking to maximize your HSA in 2026 and beyond.
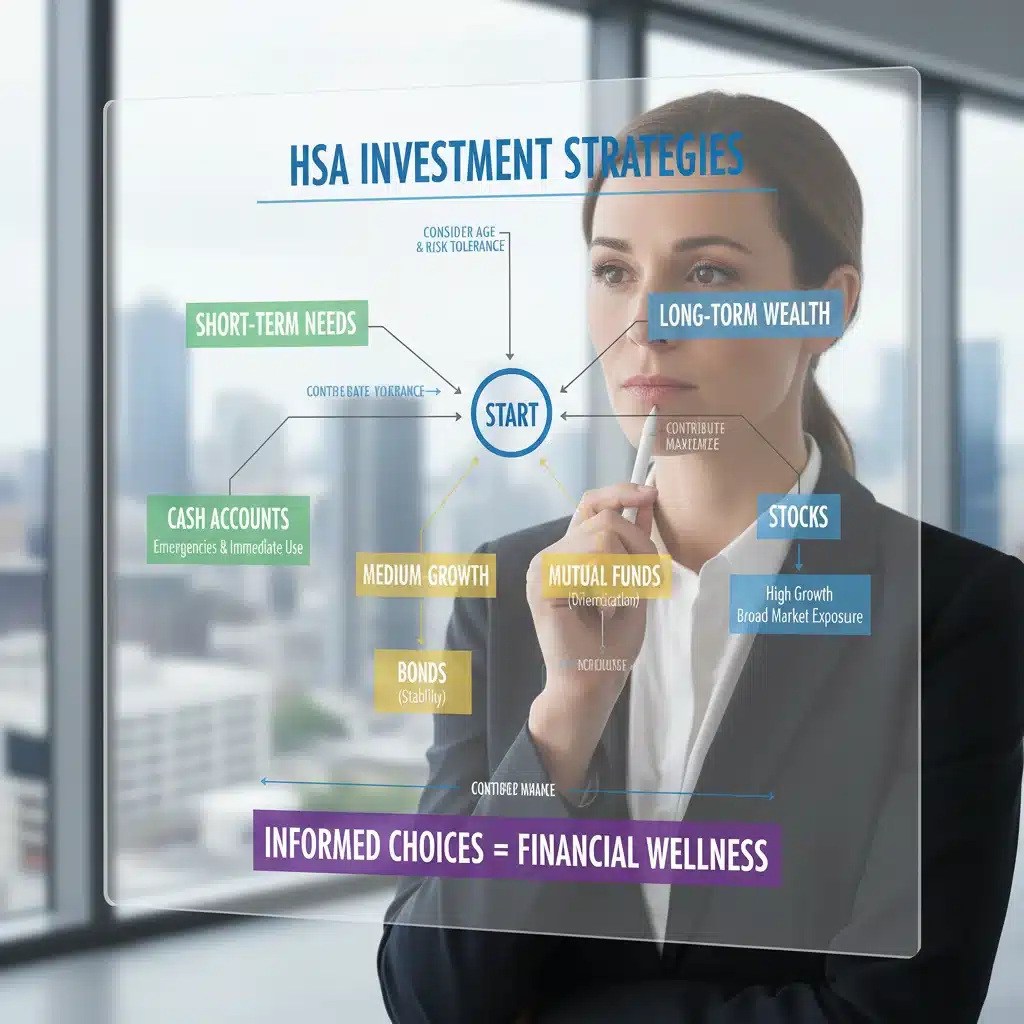
2. Diversified Investment Portfolio
Just like any other investment account, diversification is key. Most HSA providers offer a range of investment options, from low-cost index funds and ETFs to individual stocks and bonds. Your investment strategy should align with your risk tolerance and time horizon:
- Long-Term Horizon (10+ years): If you plan to use your HSA primarily for retirement healthcare expenses, a more aggressive portfolio heavily weighted towards equities (stocks) might be appropriate. Historically, stocks have provided the best long-term returns.
- Mid-Term Horizon (5-10 years): A balanced portfolio with a mix of stocks and bonds could be suitable. This offers growth potential while mitigating some market volatility.
- Short-Term Horizon (Less than 5 years): If you anticipate needing the funds sooner for known medical expenses, a more conservative approach with a higher allocation to bonds, money market funds, or even leaving a portion in cash might be prudent to protect your principal.
Regularly review and rebalance your portfolio to ensure it remains aligned with your financial goals and risk profile. This proactive management is essential to maximize your HSA in 2026 and ensure its continued growth.
3. Choosing the Right HSA Provider
Not all HSA providers are created equal. When selecting or evaluating your current provider, consider the following factors:
- Investment Options: Does the provider offer a wide range of low-cost investment options (e.g., Vanguard, Fidelity, iShares ETFs)?
- Fees: Are there monthly maintenance fees, investment fees, or trading commissions? High fees can erode your returns over time.
- Minimums: Are there minimum balances required to invest or avoid fees?
- User Experience: Is the platform easy to navigate and manage your investments?
- Customer Service: Is reliable customer support available when you need it?
If your employer-sponsored HSA has limited or high-fee investment options, you might consider transferring your funds to a different HSA provider that offers better investment choices. This is often referred to as a trustee-to-trustee transfer or a rollover, and it’s a powerful way to optimize your HSA’s investment potential. Doing so can significantly help you maximize your HSA in 2026 by ensuring your money is working as hard as possible for you.
Leveraging the HSA for Retirement Healthcare Costs
One of the most compelling reasons to maximize your HSA in 2026 is its potential as a retirement healthcare savings vehicle. Fidelity estimates that a 65-year-old couple retiring today could need approximately $315,000 to cover healthcare expenses throughout retirement. This staggering figure underscores the importance of dedicated savings, and the HSA is perfectly positioned to fill this gap.
1. The ‘Invisible’ Retirement Account
Because of its triple-tax advantage, an HSA can often be a more beneficial retirement account for healthcare than a 401(k) or IRA. While 401(k)s and IRAs offer tax deductions on contributions and tax-deferred growth, withdrawals in retirement are typically taxed as ordinary income. With an HSA, qualified medical withdrawals are entirely tax-free, even in retirement. This makes it an ideal vehicle for covering Medicare premiums, deductibles, co-pays, and other out-of-pocket medical expenses in your golden years.
2. Saving Receipts for Future Reimbursement
A smart strategy to maximize your HSA in 2026 involves paying for current medical expenses out-of-pocket and meticulously saving all your receipts. Since there’s no time limit on when you can reimburse yourself for qualified medical expenses incurred after your HSA was established, you can let your HSA investments grow for decades. Then, in retirement, you can reimburse yourself for all those past expenses, tax-free, providing a significant tax-free income stream. This is a sophisticated yet simple way to leverage your HSA’s tax benefits.
3. Understanding Qualified Medical Expenses
It’s vital to understand what constitutes a qualified medical expense. The IRS provides extensive guidance on this. Generally, these include:
- Medical, dental, and vision care
- Prescription medications
- Over-the-counter drugs with a doctor’s prescription
- Certain insurance premiums (e.g., long-term care insurance, COBRA premiums, Medicare Part A, B, D premiums, but not Medigap)
- Psychological counseling
- Acupuncture, chiropractic care, and other alternative treatments (if medically necessary)
Keeping thorough records of all medical expenses, whether paid from your HSA or out-of-pocket, is crucial for tax purposes and future reimbursement. This diligent record-keeping is a cornerstone of how to maximize your HSA in 2026 effectively.
Integrating Your HSA into Your Overall Financial Plan
To truly maximize your HSA in 2026, it should not be viewed in isolation but as an integral part of your broader financial strategy. Coordinate your HSA contributions and withdrawals with your other retirement accounts, such as 401(k)s, 403(b)s, and IRAs.
1. Prioritizing Contributions
Many financial advisors recommend the following hierarchy for savings, especially when an HSA is available:
- Contribute enough to your 401(k) to get the full employer match (free money!).
- Maximize your HSA contributions.
- Maximize contributions to your Roth IRA (if eligible) or Traditional IRA.
- Contribute additional funds to your 401(k) up to the annual limit.
- Save in taxable brokerage accounts.
This hierarchy prioritizes accounts that offer the most significant tax advantages first, with the HSA often ranking very high due to its unique triple-tax benefit. By following this approach, you’re strategically allocating your savings to optimize tax efficiency and growth, which is key to maximizing your HSA in 2026.
2. Estate Planning Considerations
While often overlooked, HSAs also have estate planning implications. Upon your death, if your spouse is the designated beneficiary, the HSA can be transferred to them tax-free, and they can continue to use it as their own HSA. If the beneficiary is someone other than your spouse, the account ceases to be an HSA and is included in the beneficiary’s gross income, though they can deduct any qualified medical expenses paid by the decedent within one year of death. Understanding these rules can help in planning how to maximize your HSA in 2026 for generational wealth transfer.
3. Navigating Changes in Health Plans
Life circumstances can change, and so can your health plan. If you switch from an HDHP to a non-HDHP, you can no longer contribute to your HSA. However, you can still use the funds already in your HSA for qualified medical expenses, and the investments will continue to grow tax-free. This flexibility means that even if your eligibility for contributions changes, the benefits of your existing HSA balance persist, reinforcing the importance of how to maximize your HSA in 2026 while you are eligible.
Common Misconceptions and Advanced Tips
Despite its popularity, several misconceptions about HSAs persist. Addressing these can further help you maximize your HSA in 2026.
Misconception 1: HSAs are ‘Use It or Lose It’
Unlike Flexible Spending Accounts (FSAs), HSAs are not ‘use it or lose it.’ The funds roll over year after year, indefinitely. This feature is fundamental to its power as a long-term savings and investment vehicle.
Misconception 2: You Can Only Use HSA Funds for Current Expenses
As discussed, you can pay for current medical expenses out-of-pocket and reimburse yourself years or even decades later, allowing your HSA funds to grow. This strategy is a cornerstone for maximizing your HSA in 2026 for retirement.
Advanced Tip: Maximize Your Catch-Up Contributions
If you are age 55 or older, don’t forget the additional $1,000 catch-up contribution. This extra amount can significantly boost your HSA balance, especially as you approach retirement when medical costs typically increase. Both spouses, if 55 or older and covered by a family HDHP, can make this catch-up contribution to their respective HSAs.
Advanced Tip: Employer Contributions and Incentives
Many employers contribute to their employees’ HSAs as part of their benefits package. These employer contributions count towards the annual IRS limit, but they are essentially free money. Always take advantage of any employer contributions available. Some employers also offer wellness incentives that contribute to your HSA, further sweetening the deal.
Conclusion: Your Path to a Healthier Financial Future in 2026
The Health Savings Account is an indispensable tool for anyone covered by a high-deductible health plan. By understanding the anticipated 2026 contribution limits, adopting savvy investment strategies, and integrating your HSA into your comprehensive financial plan, you can unlock its full potential. The triple-tax advantage, combined with its flexibility and portability, makes the HSA a standout choice for managing current healthcare costs and building a robust tax-free nest egg for retirement medical expenses.
Start planning now to maximize your HSA in 2026. Review your health plan, assess your contribution capacity, choose the right investment options, and commit to a long-term strategy. Your future self, and your wallet, will thank you.