Master Your Future: 2026 Financial & Educational Goals Strategy
Anúncios
The 2026 Daily Decision Matrix: Prioritizing Your Financial and Educational Goals
As we stand on the cusp of 2026, the horizon beckons with possibilities and challenges. The ability to effectively prioritize and strategize our financial and educational goals is not merely a desirable skill; it’s a fundamental requirement for navigating the complexities of modern life. This comprehensive guide, centered around achieving your 2026 financial education goals, will delve into practical solutions and illuminate the profound financial impact of your choices. We aim to equip you with a robust framework – a ‘Daily Decision Matrix’ – to ensure every step you take in 2026 propels you closer to your aspirations.
Anúncios
Understanding the Interconnectedness of Financial and Educational Goals
Before we construct our decision matrix, it’s crucial to recognize that financial and educational goals are not isolated entities. They are inextricably linked, each influencing and often enabling the other. Investing in education, whether formal or informal, can lead to higher earning potential, which in turn fuels financial stability and growth. Conversely, sound financial planning can provide the resources necessary to pursue educational opportunities, be it a new degree, a certification, or specialized training. For your 2026 financial education goals, this symbiotic relationship is a cornerstone of effective planning.
The Economic Landscape of 2026: What to Expect
Forecasting the economic climate for 2026 involves acknowledging current trends and potential shifts. We might see continued technological advancements reshaping industries, persistent inflation pressures, evolving job markets, and perhaps new opportunities in green economies or digital sectors. Understanding these dynamics is paramount as you set your 2026 financial education goals. For instance, if a particular industry is projected to grow, aligning your educational pursuits with the skills required in that sector can significantly enhance your career prospects and financial returns.
Anúncios
Long-Term Vision vs. Short-Term Actions
Achieving significant 2026 financial education goals requires a delicate balance between a grand long-term vision and actionable short-term steps. Your long-term vision might be to achieve early retirement or become an expert in artificial intelligence. Your short-term actions, then, are the daily, weekly, and monthly tasks that contribute to these larger objectives. The Daily Decision Matrix helps bridge this gap, ensuring that your immediate choices are always aligned with your ultimate goals.
Establishing Your 2026 Financial Goals: A Practical Approach
Defining clear, measurable, achievable, relevant, and time-bound (SMART) financial goals is the first step. For your 2026 financial education goals, this means moving beyond vague aspirations to concrete targets.
1. Financial Health Check-up
- Assess Current State: Begin by scrutinizing your current financial situation. What are your assets (savings, investments, property) and liabilities (debts like mortgages, student loans, credit card balances)?
- Track Spending: For a month or two, meticulously track every dollar you spend. This reveals where your money truly goes and highlights areas for potential savings.
- Net Worth Calculation: Calculate your net worth. This provides a baseline from which to measure progress towards your 2026 financial education goals.
2. Setting SMART Financial Targets for 2026
- Savings Goals: Do you aim to save for a down payment on a house, a new car, or an emergency fund? Specify the exact amount. For example, instead of "save more money," aim for "save $10,000 for an emergency fund by December 31, 2026."
- Debt Reduction: Identify which debts you want to tackle. "Pay off 50% of credit card debt by June 30, 2026" is a strong goal.
- Investment Growth: If you’re investing, set targets for portfolio growth or specific investment contributions. "Increase investment contributions by $200 per month starting January 2026" is actionable.
- Income Generation: Explore ways to increase income. This could be through a raise, a side hustle, or a new job. "Generate an additional $500 per month through freelance work by end of Q1 2026."
3. Budgeting and Cash Flow Management
A well-structured budget is the backbone of achieving any 2026 financial education goals. It’s not about restriction but about conscious allocation of resources.
- Zero-Based Budgeting: Assign every dollar a job. This ensures no money is left unaccountat for.
- 50/30/20 Rule: Allocate 50% of your income to needs, 30% to wants, and 20% to savings and debt repayment. Adjust these percentages to fit your unique situation and 2026 financial education goals.
- Automate Savings: Set up automatic transfers from your checking to your savings or investment accounts. This "pay yourself first" strategy is incredibly effective.
Establishing Your 2026 Educational Goals: A Growth Mindset
Education in 2026 extends far beyond traditional schooling. It encompasses continuous learning, skill acquisition, and personal development. These are crucial components of your 2026 financial education goals, as enhanced skills often lead to increased earning potential.
1. Identify Skill Gaps and Future Trends
- Industry Research: What skills are in high demand in your current or desired industry? Look at job postings, industry reports, and professional networking platforms.
- Personal Assessment: What are your strengths and weaknesses? Where do you need to improve to advance your career or pursue new opportunities?
- Future-Proofing: Consider skills that are likely to remain relevant despite technological shifts, such as critical thinking, problem-solving, creativity, and emotional intelligence.
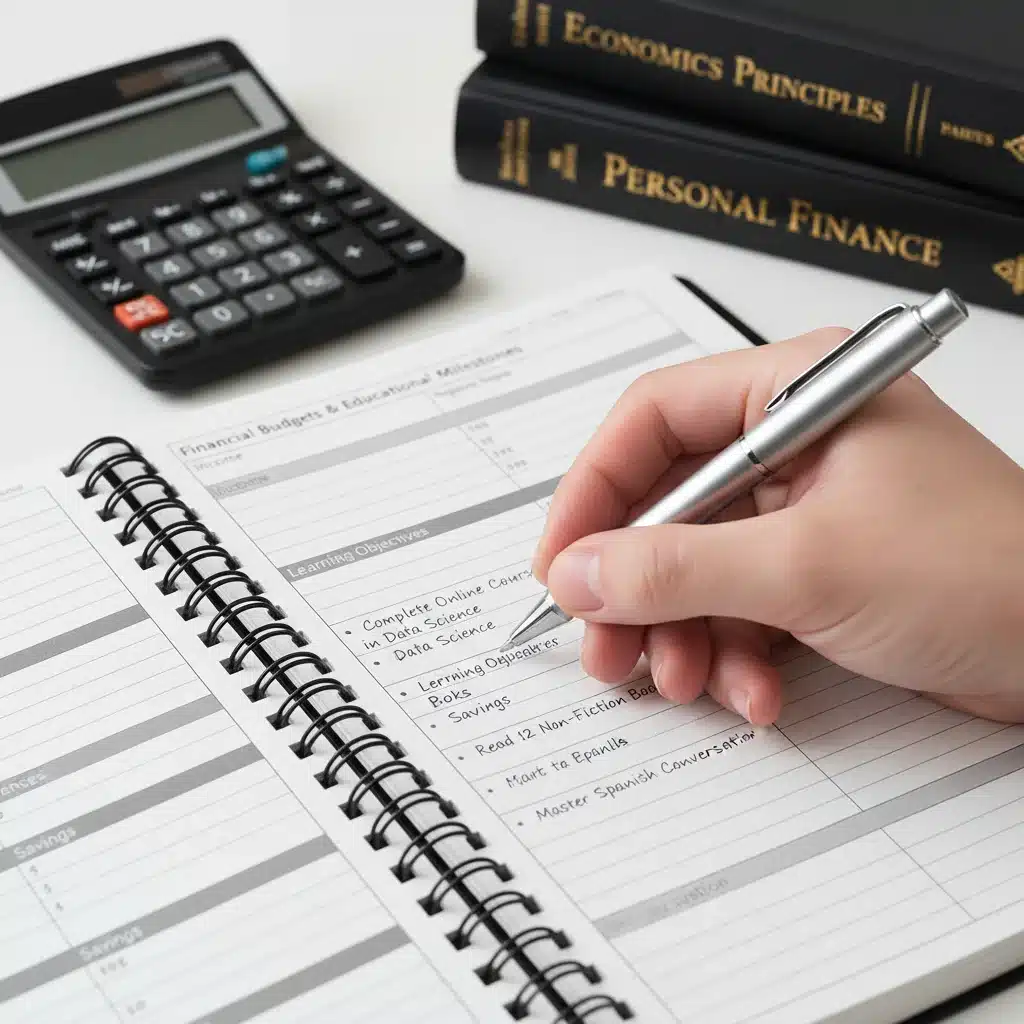
2. Setting SMART Educational Targets for 2026
- Formal Education: "Complete a Master’s degree in Data Science by December 2026" or "Enroll in a certified project management course by March 2026."
- Skill Acquisition: "Become proficient in Python programming by Q3 2026" or "Master public speaking by giving five presentations by year-end."
- Personal Development: "Read 12 books on leadership and personal growth by December 2026" or "Dedicate 30 minutes daily to learning a new language."
- Certifications: "Obtain AWS Cloud Practitioner certification by July 2026."
3. Learning Resources and Strategies
The digital age offers an unprecedented array of learning resources. Leverage them effectively to achieve your 2026 financial education goals.
- Online Courses: Platforms like Coursera, edX, Udemy, and LinkedIn Learning offer flexible and affordable options.
- Books and E-books: A traditional yet powerful way to gain knowledge.
- Workshops and Webinars: Often provide practical, hands-on experience and networking opportunities.
- Mentorship: Seek out mentors in your field who can offer guidance and support.
- Practice and Application: Learning is incomplete without application. Actively seek opportunities to use your new skills.
The Daily Decision Matrix: Prioritizing for Impact
Now that your 2026 financial education goals are clearly defined, the Daily Decision Matrix helps you prioritize tasks and make informed choices that align with these goals. This matrix is inspired by Eisenhower’s Urgent/Important matrix but tailored for financial and educational progress.
Quadrant 1: Urgent & Important (Do First)
These are tasks that demand immediate attention and significantly contribute to your 2026 financial education goals. Neglecting them has direct and often negative consequences.
- Financial: Paying bills before due dates, addressing unexpected financial emergencies (e.g., car repair), reviewing investment performance during market volatility.
- Educational: Meeting a deadline for a critical assignment, preparing for an upcoming certification exam, addressing a sudden project requirement at work that requires immediate skill application.
Quadrant 2: Important, Not Urgent (Schedule)
This is where most of your proactive 2026 financial education goals reside. These tasks are crucial for long-term success but don’t have immediate deadlines. This quadrant is where true growth happens.
- Financial: Regular budget reviews, researching new investment opportunities, setting up automatic savings transfers, meeting with a financial advisor, planning for retirement.
- Educational: Dedicating time for daily skill practice, working on a long-term course project, networking with industry professionals, reading industry publications, planning your next learning module.
Quadrant 3: Urgent, Not Important (Delegate or Minimize)
These tasks often create a false sense of urgency. While they demand your attention, they don’t significantly contribute to your core 2026 financial education goals. The key is to minimize their impact on your productive time.
- Financial: Responding to non-critical emails about promotions, dealing with minor administrative tasks that could be automated or postponed, impulse buying during sales.
- Educational: Attending non-essential meetings, getting caught up in social media discussions about your field without active learning, helping colleagues with tasks outside your core responsibilities.
Quadrant 4: Not Urgent & Not Important (Eliminate)
These are time-wasters that distract you from your 2026 financial education goals. Identify them and eliminate them from your routine.
- Financial: Excessive online browsing for non-essential purchases, spending hours on financial news without taking action, engaging in speculative ‘get-rich-quick’ schemes.
- Educational: Mindless scrolling through social media, watching excessive entertainment, engaging in unproductive discussions, procrastination.
Practical Solutions for Overcoming Obstacles
Even with a clear matrix, challenges will arise. Here are practical solutions to keep your 2026 financial education goals on track.
Financial Obstacles & Solutions:
- Unexpected Expenses: Build and maintain an emergency fund (3-6 months of living expenses) to cushion against financial shocks.
- Income Stagnation: Actively seek opportunities for raises, promotions, or develop a side hustle. Your educational goals can directly address this by acquiring in-demand skills.
- Debt Overwhelm: Implement a debt snowball or avalanche method. Consider consolidating high-interest debts.
- Lack of Discipline: Automate savings and investments. Use budgeting apps to stay accountable. Find an accountability partner.
Educational Obstacles & Solutions:
- Time Constraints: Block out dedicated time for learning in your calendar. Utilize micro-learning strategies (e.g., 15-minute learning sessions). Prioritize learning tasks in Quadrant 2.
- Lack of Motivation: Remind yourself of your ‘why.’ Break down large goals into smaller, manageable steps. Celebrate small victories. Connect with a learning community.
- Information Overload: Focus on one or two key learning objectives at a time. Be selective about your learning resources.
- Cost of Education: Explore free online resources, scholarships, grants, and company-sponsored training programs. Remember, your 2026 financial education goals should be financially sustainable.
Measuring Progress and Adapting Your Strategy
Achieving your 2026 financial education goals is an iterative process. Regular review and adaptation are crucial.
1. Regular Review Sessions
- Weekly Check-ins: Dedicate 15-30 minutes each week to review your progress against your Daily Decision Matrix. What did you accomplish? What fell short? Why?
- Monthly Deep Dives: At the end of each month, review your financial statements, educational progress, and overall goal alignment. Adjust your budget or learning plan as needed.
- Quarterly Strategic Planning: Every three months, take a broader look. Are your 2026 financial education goals still relevant? Do you need to pivot due to unforeseen circumstances or new opportunities?
2. Key Performance Indicators (KPIs)
Define specific KPIs for both your financial and educational objectives.
- Financial KPIs: Savings rate, debt-to-income ratio, net worth growth, investment portfolio performance, passive income generated.
- Educational KPIs: Course completion rates, new skills acquired (demonstrated through projects or certifications), networking connections made, salary increase due to new skills.
3. Flexibility and Resilience
Life is unpredictable. Your plan for 2026 financial education goals must be flexible enough to accommodate changes without derailing your entire strategy. Develop resilience by viewing setbacks as learning opportunities rather than failures. The ability to adapt is often more valuable than rigid adherence to an outdated plan.
The Financial Impact of Prioritizing Your Goals
The conscious effort to prioritize your 2026 financial education goals yields substantial financial benefits, both immediate and long-term.
Immediate Benefits:
- Reduced Stress: Knowing you have a clear plan and are making progress significantly lowers financial and career-related stress.
- Better Cash Flow: Effective budgeting and debt management free up cash for savings and investments.
- Increased Savings: Consistent prioritization leads to a faster accumulation of emergency funds and investment capital.
Long-Term Benefits:
- Wealth Accumulation: Disciplined saving and smart investing, fueled by enhanced earning potential from education, lead to significant wealth over time.
- Career Advancement: Targeted educational pursuits open doors to promotions, higher-paying jobs, and new career paths. This directly impacts your 2026 financial education goals.
- Financial Independence: The ultimate goal for many, achieved through consistent adherence to financial and educational strategies.
- Improved Quality of Life: Financial security and continuous personal growth contribute to a more fulfilling and secure life.
Case Studies: Real-World Application of the Matrix
Case Study 1: Sarah, The Aspiring Tech Professional
Sarah, a marketing professional, aimed to transition into tech by end of 2026. Her 2026 financial education goals included saving for a coding bootcamp and acquiring Python and SQL skills. Using the Daily Decision Matrix:
- Q1 (Urgent & Important): Paying off a high-interest credit card to free up cash for bootcamp.
- Q2 (Important, Not Urgent): Scheduling 2 hours daily for online Python courses, networking with tech professionals on LinkedIn, setting up automatic transfers to her ‘bootcamp fund.’
- Q3 (Urgent, Not Important): Delegating minor marketing administrative tasks to a junior team member to free up learning time.
- Q4 (Not Urgent & Not Important): Significantly reducing social media browsing and excessive TV watching.
By December 2026, Sarah had not only completed her bootcamp but also secured an entry-level data analyst position, exceeding her initial salary expectations due to her focused approach to her 2026 financial education goals.
Case Study 2: Mark, The Small Business Owner
Mark wanted to expand his e-commerce business and optimize his personal finances by 2026. His 2026 financial education goals involved increasing business profit by 30% and building a robust personal investment portfolio. Using the Matrix:
- Q1 (Urgent & Important): Addressing immediate cash flow issues in his business, fulfilling customer orders promptly.
- Q2 (Important, Not Urgent): Enrolling in an online course on advanced digital marketing, dedicating time to research new product lines, meeting with a financial advisor to diversify his personal investments, automating monthly contributions to a Roth IRA.
- Q3 (Urgent, Not Important): Responding to non-critical vendor emails at specific times rather than instantly, minimizing time spent on minor website tweaks that don’t impact sales.
- Q4 (Not Urgent & Not Important): Eliminating unproductive meetings and excessive news consumption.
By the end of 2026, Mark’s business profit increased by 35%, and his investment portfolio saw substantial growth, directly attributable to his strategic focus on his 2026 financial education goals.
Conclusion: Your Roadmap to a Successful 2026
The journey to achieving your 2026 financial education goals is a marathon, not a sprint. It demands foresight, discipline, and the agility to adapt. By implementing the Daily Decision Matrix, you gain a powerful tool for prioritizing tasks, making intentional choices, and ensuring that every action you take contributes meaningfully to your overarching objectives.
Remember, success in 2026 isn’t about working harder; it’s about working smarter. It’s about making conscious, strategic decisions daily that compound over time, transforming your aspirations into tangible realities. Start today by defining your SMART goals, understanding their interconnectedness, and committing to the proactive management of your time and resources. Your future self will thank you for the strategic choices you make to achieve your 2026 financial education goals.
Key Takeaways:
- Interconnectedness: Financial and educational goals are mutually reinforcing.
- SMART Goals: Define clear, measurable, achievable, relevant, and time-bound objectives.
- Budgeting: Master cash flow management through effective budgeting.
- Skill Development: Continuously acquire in-demand skills to enhance earning potential.
- Decision Matrix: Use the Urgent/Important framework to prioritize daily tasks.
- Adaptability: Regularly review progress and be flexible in your strategy.
- Financial Impact: Prioritization leads to reduced stress, increased wealth, and career advancement.
Embark on 2026 with confidence, armed with a clear vision and a practical framework for success. Your financial and educational triumphs await!
Author