Decoding the 2026 Social Security COLA: What It Means for Your Benefits
Anúncios
Decoding the 2026 Social Security COLA: What It Means for Your Benefits
Anúncios
As we navigate the ever-evolving landscape of economic shifts, one crucial factor consistently stands out for retirees and beneficiaries: the Social Security Cost-of-Living Adjustment, or COLA. For millions of Americans, COLA is not just an acronym; it’s a vital mechanism designed to help their benefits keep pace with inflation, preserving their purchasing power year after year. As we look ahead, understanding the nuances of the 2026 Social Security COLA becomes increasingly important for effective financial planning and ensuring long-term security.
The prospect of the 2026 Social Security COLA sparks both anticipation and questions. How will it be calculated? What economic indicators will influence its size? And most importantly, what will it mean for your monthly benefits? This comprehensive guide aims to demystify the 2026 Social Security COLA, providing you with a clear understanding of its mechanics, historical context, and potential impact on your financial future. We’ll explore the factors that drive this adjustment, offer insights into projections, and equip you with the knowledge to prepare for whatever the future holds for your Social Security benefits.
For many, Social Security represents a cornerstone of their retirement income. Without regular adjustments to account for inflation, the real value of these benefits would erode over time, making it challenging for beneficiaries to maintain their standard of living. The COLA serves as a critical safeguard against this erosion, ensuring that the financial support provided by Social Security remains relevant and effective. Therefore, staying informed about the 2026 Social Security COLA is not merely a matter of curiosity but a fundamental aspect of prudent financial management for anyone relying on these benefits.
Anúncios
Understanding the Social Security COLA: The Basics
Before delving into the specifics of the 2026 Social Security COLA, it’s essential to grasp the fundamental principles behind this annual adjustment. What exactly is COLA, and why is it so important? At its core, the Cost-of-Living Adjustment is an increase in Social Security benefits and Supplemental Security Income (SSI) payments that helps to offset the effects of inflation. Its primary goal is to ensure that the purchasing power of beneficiaries’ income does not diminish over time due to rising prices for goods and services.
How is COLA Calculated? The CPI-W Connection
The calculation of the Social Security COLA is tied directly to inflation, specifically measured by the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). This particular index tracks the prices of a basket of goods and services commonly purchased by urban wage earners and clerical workers. The Social Security Administration (SSA) uses a specific period to determine the annual COLA. The COLA for a given year is based on the increase in the CPI-W from the third quarter of the previous year to the third quarter of the current year.
More precisely, the COLA is the percentage increase in the CPI-W from the average for the third quarter (July, August, September) of the last year a COLA was payable to the average for the third quarter of the current year. If there is no increase, or if the average decreases, there is no COLA. This methodology ensures that the adjustment directly reflects the inflationary pressures experienced by a significant portion of the population.
The Importance of COLA for Beneficiaries
Imagine a scenario where your income remains fixed while the cost of groceries, utilities, and healthcare steadily climbs. This is precisely the challenge COLA aims to address. For retirees, disabled individuals, and survivors who depend on Social Security, these benefits often represent a substantial, if not primary, source of income. Without the annual COLA, the real value of their benefits would erode, potentially leading to financial hardship and a reduced quality of life.
The COLA acts as a vital safety net, helping beneficiaries maintain their purchasing power and meet their essential needs. It acknowledges that the cost of living is not static and that fixed incomes need to adapt to economic realities. Therefore, each year’s COLA announcement is eagerly anticipated, as it directly impacts the financial stability of millions of Americans. Understanding this mechanism is the first step in appreciating the significance of the 2026 Social Security COLA.
Historical Context of Social Security COLA
To fully appreciate the potential implications of the 2026 Social Security COLA, it’s beneficial to examine its historical trajectory. The concept of an automatic cost-of-living adjustment for Social Security benefits was signed into law in 1972 and took effect in 1975. Before this, benefit increases required an act of Congress, making them less predictable and often subject to political considerations. The automatic COLA mechanism removed this uncertainty, providing a more reliable system for beneficiaries.
Past COLA Trends and Their Drivers
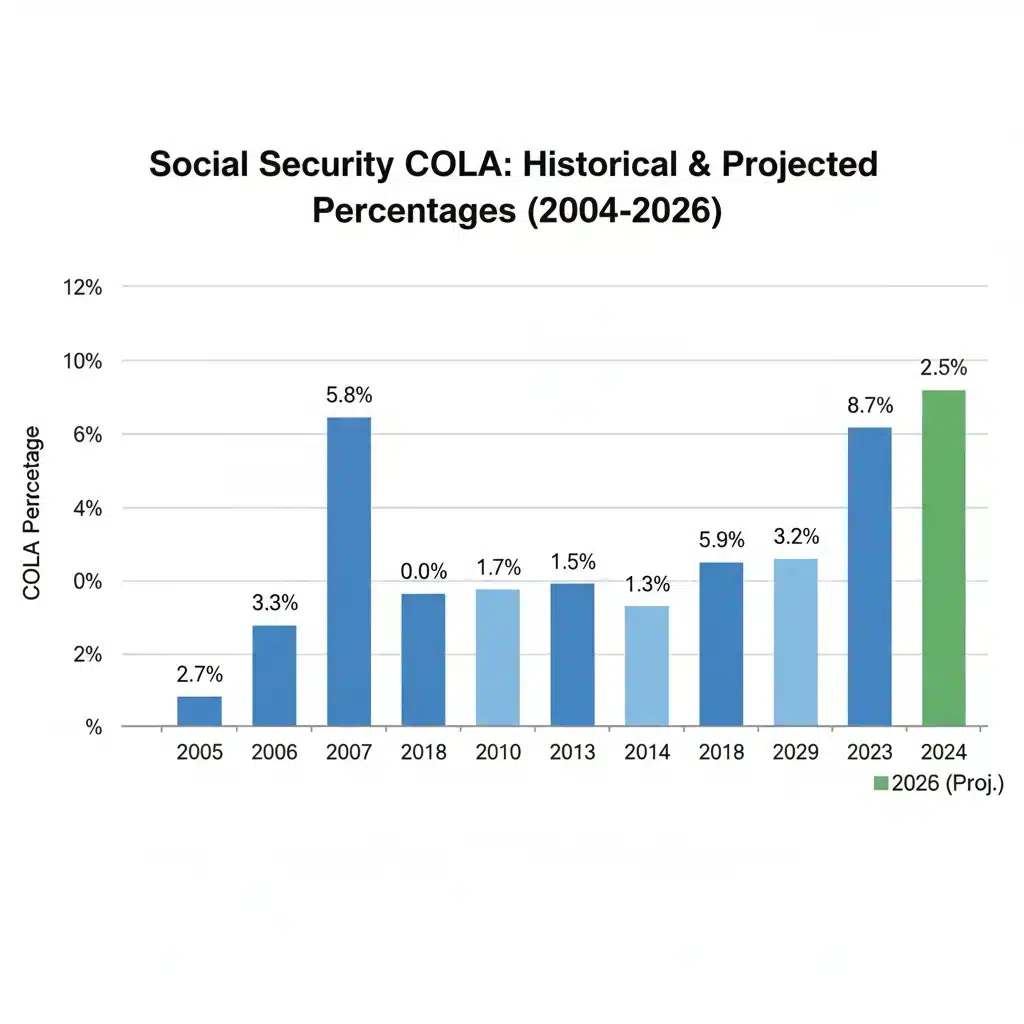
Over the decades, COLA percentages have varied significantly, reflecting the dynamic nature of inflation. In periods of high inflation, such as the late 1970s and early 1980s, COLA adjustments were substantial, sometimes reaching double-digit percentages. Conversely, during periods of low inflation or even deflation, COLA has been minimal or, in some rare instances, zero.
For example, in 2009, 2010, and 2011, there was no COLA due to the economic downturn and low inflation following the Great Recession. More recently, we’ve seen a resurgence in significant COLA increases, particularly in 2022 and 2023, as global economic factors and supply chain issues contributed to higher inflation rates. These historical trends underscore the direct correlation between the broader economic environment and the size of the annual COLA.
Why History Matters for the 2026 Social Security COLA
Studying past COLA trends offers valuable insights into what might influence the 2026 Social Security COLA. While past performance is not a guarantee of future results, it helps us understand the sensitivity of the COLA to economic indicators like energy prices, food costs, and overall consumer demand. Periods of robust economic growth often come with inflationary pressures, leading to higher COLAs, while economic slowdowns or recessions can suppress inflation and result in lower or no adjustments.
Moreover, the political and social context surrounding inflation can also play a role, even if indirectly. Public sentiment and government policies aimed at controlling inflation can influence the economic environment that ultimately determines the CPI-W. Therefore, a comprehensive understanding of historical COLA adjustments provides a solid foundation for anticipating and interpreting the upcoming 2026 Social Security COLA.
Factors Influencing the 2026 Social Security COLA
Predicting the exact percentage of the 2026 Social Security COLA is challenging, as it depends on economic data that will unfold over the next year and a half. However, we can identify the key factors and economic indicators that will most heavily influence its determination. These elements are constantly monitored by economists, financial analysts, and, of course, the Social Security Administration itself.
Inflation Trends: The Primary Driver
As established, inflation is the paramount factor. Specifically, the CPI-W data from the third quarter of 2025 will be the ultimate determinant. Therefore, economists will be closely watching a range of inflationary pressures throughout 2024 and 2025. These include:
- Energy Prices: Fluctuations in crude oil, natural gas, and gasoline prices have a significant ripple effect across the economy, impacting transportation costs, manufacturing, and consumer spending.
- Food Costs: Global supply chain issues, weather patterns, and agricultural output can lead to volatility in food prices, which are a substantial component of household budgets.
- Housing Costs: Rent and homeowner equivalent rent are significant components of the CPI. Rising housing costs can exert upward pressure on overall inflation.
- Healthcare Expenses: Medical care services and prescription drug costs continue to be a major concern for many, particularly seniors, and contribute to the overall inflation picture.
- Supply Chain Dynamics: Ongoing global supply chain stability or disruptions can impact the availability and cost of goods, influencing inflation.
Any sustained increase in these areas during the measurement period for the 2026 Social Security COLA would likely translate into a higher adjustment, while a moderation or decline would lead to a lower one.
Economic Growth and Wage Increases
While CPI-W is the direct measure, broader economic conditions also play a role. Strong economic growth often correlates with higher demand for goods and services, which can lead to inflation. Similarly, robust wage growth, while beneficial for workers, can also contribute to inflationary pressures if not matched by productivity gains. Conversely, an economic slowdown or recession typically dampens inflation, potentially leading to a smaller 2026 Social Security COLA.
Federal Reserve Policy
The actions of the Federal Reserve are crucial. By raising or lowering interest rates, the Fed attempts to manage inflation and stimulate or cool down the economy. A hawkish stance (raising rates) is typically aimed at curbing inflation, which could lead to a lower COLA. A dovish stance (lowering rates) might be adopted during economic slowdowns, potentially allowing inflation to rise and thus influencing the COLA upwards.
Global Events
Geopolitical events, international conflicts, and global economic shifts can have profound impacts on inflation. For instance, disruptions to global energy markets or trade routes can significantly influence prices domestically. These unpredictable events add another layer of complexity to forecasting the 2026 Social Security COLA.
Projecting the 2026 Social Security COLA
Forecasting the 2026 Social Security COLA this far in advance is inherently speculative, as many economic variables can change. However, financial institutions, economists, and advocacy groups often release early projections based on current trends and economic models. These projections should be viewed as educated estimates rather than definitive figures.
Initial Forecasts and Their Basis
Early projections for the 2026 Social Security COLA typically begin to emerge in late 2024 and early 2025. These initial forecasts usually rely on:
- Current Inflation Trajectories: If inflation remains elevated or shows signs of persistent growth, early COLA estimates will lean higher. If inflation is moderating, estimates will be lower.
- Federal Reserve Projections: The Fed’s own outlook on inflation and economic growth provides a benchmark for many forecasters.
- Consensus Economic Forecasts: Analysts often aggregate projections from various economic models and surveys to arrive at a consensus.
It’s important to remember that these are early-stage predictions. The actual COLA will not be announced until October 2025, after the third-quarter CPI-W data becomes available.
How to Interpret COLA Projections
When you encounter projections for the 2026 Social Security COLA, consider the following:
- Source Credibility: Rely on reputable financial news outlets, government agencies (like the Congressional Budget Office), and established economic research firms.
- Assumptions Made: Understand what underlying economic assumptions are being used in the forecast (e.g., oil prices, interest rates, GDP growth). Significant deviations from these assumptions could alter the actual COLA.
- Range of Estimates: Instead of focusing on a single number, look for a range of possible outcomes. This acknowledges the inherent uncertainty in long-term economic forecasting.
For beneficiaries, these projections are useful for preliminary financial planning, but flexibility is key. Your actual benefit increase will only be known once the official announcement is made.
Impact of the 2026 Social Security COLA on Your Benefits
The direct impact of the 2026 Social Security COLA on your benefits is straightforward: if there’s a positive COLA, your monthly payment will increase by that percentage. However, the indirect effects and broader implications for your financial planning are worth exploring in detail.
Direct Increase in Monthly Payments
Let’s say, for example, the 2026 Social Security COLA is determined to be 3.0%. If your current monthly benefit is $1,800, your new benefit would be $1,800 * 1.03 = $1,854. This $54 increase helps to maintain your purchasing power against rising costs. This adjustment takes effect starting in January 2026.
It’s crucial to remember that the COLA applies to your primary insurance amount (PIA), which is the benefit you receive at your full retirement age. Benefits claimed earlier or later are adjusted based on their own calculations, but the COLA percentage itself is uniformly applied to the base amount.
Potential Impact on Medicare Part B Premiums
One significant consideration that often accompanies COLA announcements is its interaction with Medicare Part B premiums. By law, a provision known as the ‘hold harmless’ clause prevents most Social Security beneficiaries from seeing their net Social Security benefit decrease due to an increase in Medicare Part B premiums. This means that if your Part B premium increase is larger than your COLA increase, your Part B premium will be adjusted so that your net Social Security payment does not go down.
However, this provision doesn’t apply to all beneficiaries. It generally doesn’t apply to high-income earners who pay income-related monthly adjustment amounts (IRMAA), new Medicare enrollees, or those who pay their Part B premiums directly rather than having them deducted from their Social Security benefits. Therefore, while the 2026 Social Security COLA will directly boost your gross benefit, the net increase might be partially or fully offset by rising Medicare costs for some individuals.
Taxation of Social Security Benefits
Another factor to consider is the taxation of Social Security benefits. Depending on your combined income (which includes your adjusted gross income, tax-exempt interest, and half of your Social Security benefits), a portion of your Social Security benefits may be subject to federal income tax. As your benefits increase due to COLA, your combined income might also rise, potentially pushing you into a higher tax bracket for Social Security taxation, or making a larger portion of your benefits taxable.
This is an important point for financial planning. A higher 2026 Social Security COLA is positive for purchasing power, but it’s essential to factor in potential tax implications when calculating your net disposable income.
Financial Planning with the 2026 Social Security COLA in Mind
Regardless of the size of the 2026 Social Security COLA, proactive financial planning is paramount. Understanding how this adjustment fits into your broader financial picture can help you make informed decisions and ensure your retirement remains secure.
Budgeting and Expense Management
The first step is to integrate the anticipated COLA into your annual budget. While the exact figure won’t be known until late 2025, you can use conservative estimates for your planning. If you anticipate a modest COLA, ensure your budget can accommodate potential increases in everyday expenses without relying solely on a significant benefit boost. Regularly reviewing your spending and identifying areas for adjustment is always a good practice.
Considering Other Income Sources
Social Security is often just one component of a comprehensive retirement income strategy. If you have other income sources, such as pensions, 401(k) withdrawals, or investment income, consider how the 2026 Social Security COLA interacts with these. For instance, if your investment portfolio is performing well, a smaller COLA might have less impact on your overall financial health. Conversely, if Social Security is your primary income, a strong COLA becomes even more critical.
Long-Term Financial Projections
For long-term planning, it’s wise to use realistic assumptions about future COLA adjustments. Many financial planners use an average historical COLA rate (e.g., 2-3%) in their projections rather than assuming consistently high or low increases. This conservative approach helps to build resilience into your retirement plan, ensuring it can withstand periods of lower COLAs or higher inflation.
Seeking Professional Advice
Navigating the complexities of Social Security, Medicare, and retirement planning can be daunting. A qualified financial advisor can provide personalized guidance, helping you understand how the 2026 Social Security COLA and other factors will affect your unique situation. They can assist with tax planning, investment strategies, and overall wealth management to optimize your financial well-being.
Beyond 2026: The Future of Social Security and COLA
While our focus is on the 2026 Social Security COLA, it’s important to consider the broader long-term outlook for Social Security. The system faces ongoing financial challenges, primarily due to demographic shifts (an aging population and lower birth rates) and increasing life expectancies. These challenges could potentially impact future COLA calculations or the structure of benefits themselves.
Trust Fund Solvency
The Social Security Trust Funds are projected to be able to pay 100% of promised benefits until around the mid-2030s. After that, if Congress does not act, the system would only be able to pay about 80% of scheduled benefits from ongoing tax revenues. While this does not mean Social Security will run out of money, it does highlight the need for legislative action to ensure long-term solvency.
Potential solutions being discussed include raising the full retirement age, increasing the Social Security payroll tax rate, modifying the COLA calculation method (e.g., using a different inflation index like the Chained CPI-W, which tends to produce lower COLAs), or adjusting the benefit formula. Any of these changes could have significant implications for future beneficiaries and the size of subsequent COLAs.
Potential COLA Formula Changes
There have been discussions in policy circles about potentially changing the index used to calculate COLA. One alternative often proposed is the Chained Consumer Price Index for All Urban Consumers (C-CPI-U). The Chained CPI typically shows lower inflation rates because it accounts for how consumers change their purchasing habits in response to price changes (e.g., buying chicken instead of beef if beef prices rise significantly). If such a change were implemented, future COLAs, including those beyond 2026, would likely be smaller, leading to slower growth in benefits over time.
While such changes are not imminent for the 2026 Social Security COLA, beneficiaries and future retirees should remain aware of these ongoing discussions. Understanding the potential for legislative reform is crucial for long-term financial planning and advocacy.
Conclusion: Staying Informed and Prepared for the 2026 Social Security COLA
The 2026 Social Security COLA represents an essential annual adjustment that directly impacts the financial well-being of millions of Americans. While its exact percentage remains an open question, contingent on economic data yet to be collected, understanding the mechanisms behind it, its historical context, and the factors that influence it empowers you to plan more effectively.
From the direct increase in your monthly payments to the potential interplay with Medicare premiums and tax obligations, every aspect of the COLA deserves attention. By staying informed about inflation trends, economic forecasts, and the broader discussions surrounding Social Security reform, you can make proactive financial decisions that safeguard your retirement income.
As the official announcement for the 2026 Social Security COLA approaches in October 2025, remember to consult reliable sources for the most accurate information. Integrate this vital adjustment into your financial planning, and consider seeking professional advice to ensure your strategies are robust and adaptable. Your financial security in retirement is a journey, and understanding the COLA is a crucial step along the way.
Author