US Housing Market 2026: Expert Predictions & Potential 7% Price Correction by Q3
Anúncios
The United States housing market is a dynamic and often unpredictable entity, constantly influenced by a myriad of economic, social, and demographic factors. As we look towards 2026, many homeowners, prospective buyers, and investors are eager to understand what the future holds. Our deep dive into the US Housing Market 2026 aims to provide comprehensive insights, drawing on expert predictions and analyzing key indicators that could shape the landscape of real estate in the coming years. A significant point of discussion among analysts is the potential for a 7% price correction by Q3 2026, a forecast that warrants careful examination.
Understanding the trajectory of the housing market requires more than just glancing at current headlines. It involves a nuanced analysis of interest rates, inflation, supply and demand dynamics, employment figures, and even global economic stability. For anyone involved in real estate, whether as a primary residence owner or an astute investor, staying ahead of these trends is paramount. This article will break down the complex forces at play, offering an ‘insider knowledge’ perspective to help you navigate the anticipated shifts.
Anúncios
Decoding the 7% Price Correction by Q3 2026
The prediction of a 7% price correction in the US Housing Market 2026 by the third quarter is a forecast that has garnered significant attention. But what exactly does this mean, and what factors could lead to such a decline? A price correction refers to a short-term reversal in the price trend of an asset after a period of overvaluation or rapid growth. It’s not necessarily a market crash, but rather a recalibration. Several critical elements contribute to this projection:
Rising Interest Rates and Affordability Constraints
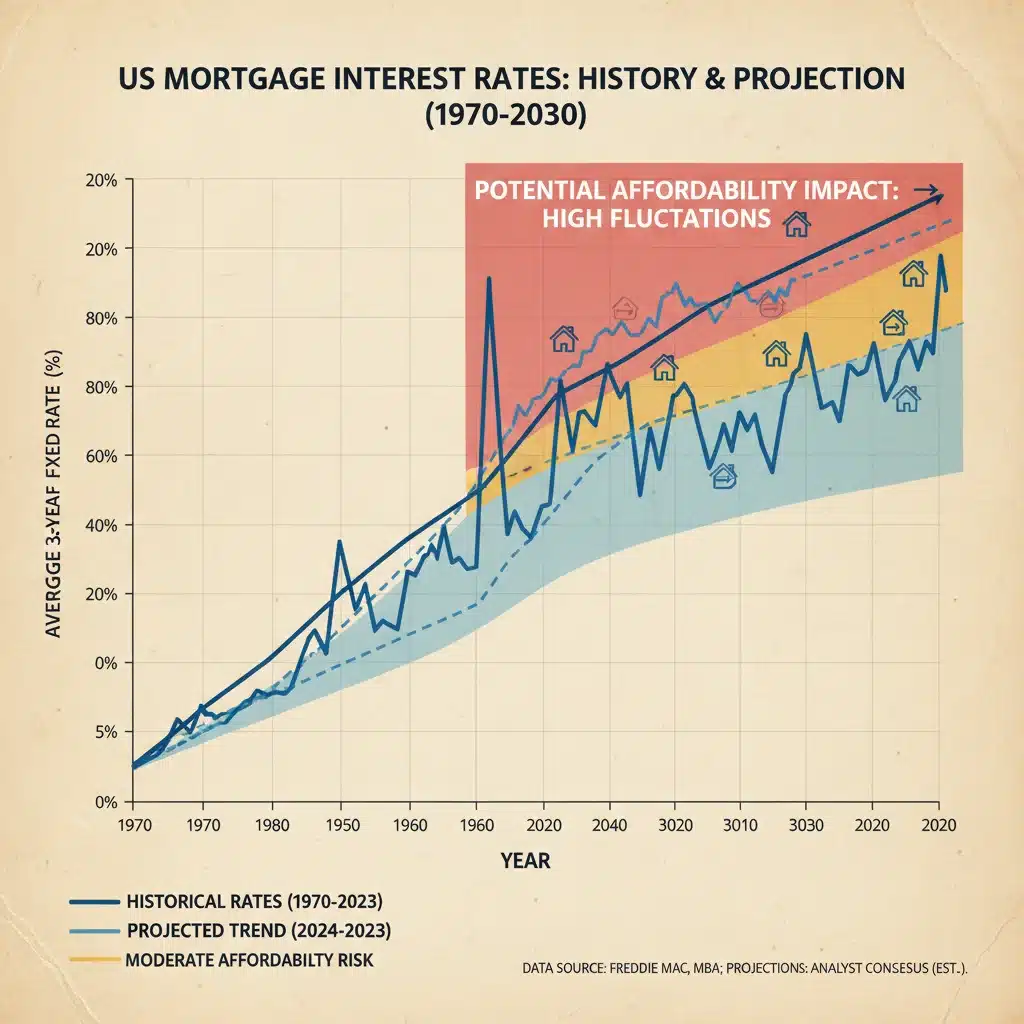
One of the most potent forces influencing housing prices is the trajectory of interest rates. The Federal Reserve’s monetary policy, driven by inflation concerns, plays a pivotal role. Higher interest rates directly translate to higher mortgage costs, reducing buying power and dampening demand. If interest rates continue to climb or remain elevated through 2025 and into 2026, the cost of homeownership could become prohibitive for a larger segment of the population. This reduction in effective demand inevitably puts downward pressure on prices.
Anúncios
Affordability has been a persistent challenge in many markets. Even with a modest correction, homes in high-demand areas may still be expensive. However, a 7% correction could provide some relief, making homeownership a possibility for those who have been priced out. The extent of this relief will, of course, depend on individual market dynamics and local income levels.
Inventory Levels and Supply Dynamics
The chronic shortage of housing supply has been a primary driver of price appreciation over the past few years. However, there’s growing evidence that new construction, though still lagging in many areas, is slowly catching up. Furthermore, if higher interest rates prompt some existing homeowners to defer selling their current homes to avoid higher mortgage rates on a new purchase, it could paradoxically free up some inventory from those who must sell. Conversely, if economic uncertainty leads to more listings, supply could outstrip demand more significantly.
A balanced market typically has a 5-6 month supply of homes. Many regions are still below this threshold, but a gradual increase in inventory, combined with cooling demand due to affordability issues, could contribute to the projected price correction. The US Housing Market 2026 will heavily depend on this delicate balance between new listings and buyer appetite.
Economic Slowdown and Recessionary Fears
The broader economic climate is inextricably linked to the health of the housing market. Persistent inflation, geopolitical instability, and a potential global economic slowdown could all contribute to a more cautious consumer sentiment. If a recessionary period materializes or intensifies, job security concerns could lead prospective buyers to postpone large purchases like homes. A weaker economy also impacts investors, who might pull back from the market, further reducing demand. This macro-economic uncertainty is a significant factor underpinning the 7% correction forecast.
Key Indicators to Watch for the US Housing Market 2026
To accurately gauge the direction of the US Housing Market 2026, several key indicators must be closely monitored. These metrics provide a snapshot of the market’s health and offer clues about future movements:
Mortgage Interest Rates
As discussed, interest rates are paramount. Keep an eye on the Federal Reserve’s statements regarding inflation and future rate hikes. The 30-year fixed-rate mortgage is the benchmark. Any sustained movement above current levels could accelerate a slowdown, while a significant drop could re-ignite demand. The interplay between inflation and central bank policy will be critical.
Inflation Trends
Inflation not only influences interest rates but also impacts household budgets. High inflation erodes purchasing power, making it harder for individuals to save for a down payment or manage monthly mortgage payments. A sustained decrease in inflation could lead to more stable interest rates and improved affordability, potentially mitigating the severity of any correction. Conversely, stubbornly high inflation could force the Fed’s hand, leading to further rate increases.
Employment and Wage Growth
A robust job market with healthy wage growth supports housing demand and affordability. When people feel secure in their jobs and see their incomes rising, they are more likely to invest in real estate. Conversely, a weakening job market, characterized by layoffs and stagnant wages, reduces the pool of eligible buyers and increases the risk of defaults among existing homeowners. The unemployment rate and average hourly earnings reports are vital statistics.
Housing Inventory Levels
The number of homes available for sale is a direct measure of supply. A rising inventory indicates that the market is becoming more balanced, or even shifting towards a buyer’s market. A falling inventory suggests continued competition among buyers. Tracking months of supply (how long it would take to sell all current homes on the market at the current sales pace) provides a clearer picture of market equilibrium.
New Construction Starts and Permits
New construction is crucial for addressing the long-term housing supply deficit. Monitoring housing starts (when construction begins) and building permits (authorization to build) provides insight into future inventory. A significant increase in these figures could signal a future easing of supply constraints, which would naturally impact prices in the US Housing Market 2026.
Regional Variations and Hotspots in the US Housing Market 2026
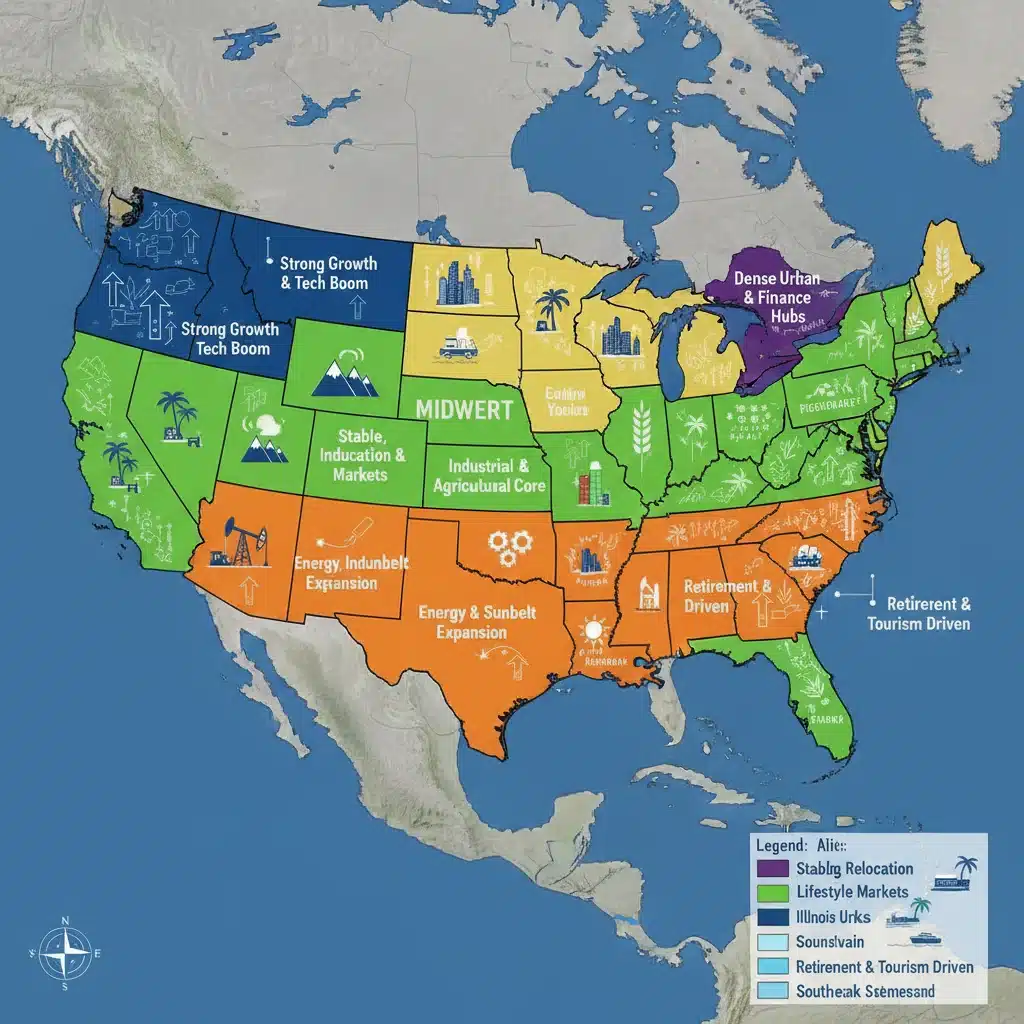
It is crucial to remember that the US Housing Market 2026 is not monolithic. National averages often mask significant regional disparities. While some areas may experience a 7% correction, others might see more modest adjustments or even continued appreciation, albeit at a slower pace. The factors driving these regional differences include:
Sun Belt Boomtowns
Regions like Florida, Texas, and parts of the Southwest have seen explosive growth over the past few years, driven by migration, lower taxes, and job opportunities. These areas might be more susceptible to corrections if speculative buying was prevalent or if job growth slows. However, strong underlying demographic trends could provide a floor for prices.
Coastal Metros
Expensive coastal cities like New York, San Francisco, and Los Angeles have historically been resilient but are also highly sensitive to interest rate changes due to their already high price points. A 7% correction in these markets, while significant, might still leave homes largely unaffordable for many, but could offer opportunities for high-net-worth buyers or those with substantial equity.
Midwest and Mountain States
Many Midwest cities offer greater affordability and have seen more stable, albeit slower, appreciation. These markets might be less prone to sharp corrections due to their balanced supply and demand dynamics and less speculative activity. Mountain states, particularly those with strong outdoor recreation economies, have seen significant influxes of remote workers, and their trajectories will depend on sustained migration patterns and local economic diversification.
Impact of Remote Work
The lasting impact of remote work continues to shape regional demand. While the initial surge into suburban and rural areas has somewhat stabilized, the ability to work from anywhere still influences migration patterns and housing preferences, affecting local market dynamics well into 2026.
Strategies for Buyers and Sellers in the Evolving Market
Understanding the potential shifts in the US Housing Market 2026 is only half the battle. Developing a strategic approach based on these insights is crucial for both buyers and sellers.
For Prospective Buyers: Patience and Preparation
- Exercise Patience: If the 7% price correction materializes, waiting until Q3 2026 or later could result in more favorable pricing. However, timing the market perfectly is notoriously difficult.
- Strengthen Your Financial Position: Focus on improving your credit score, paying down debt, and saving a larger down payment. A stronger financial profile will give you more leverage and better mortgage terms, especially if rates remain elevated.
- Get Pre-Approved, Not Just Pre-Qualified: A full pre-approval demonstrates serious intent and gives you a clear understanding of what you can afford.
- Research Local Markets: Don’t rely solely on national headlines. Understand the specific dynamics of the areas you’re interested in. Some neighborhoods might be more resilient than others.
- Consider ‘House Hacking’ or Multi-Family: If affordability remains a challenge, exploring options like multi-family homes where rental income can offset mortgage costs might be a viable strategy.
For Current Homeowners and Potential Sellers: Strategic Timing
- Evaluate Your Equity: Understand how much equity you have in your home. A correction could reduce this, so assess your financial position carefully.
- Prepare Your Home: If you plan to sell, invest in necessary repairs and staging to maximize your home’s appeal and command the best possible price, even in a cooling market.
- Be Realistic About Pricing: In a market experiencing a correction, overpricing your home can lead to longer listing times and eventual price reductions. Work with a knowledgeable real estate agent to price competitively.
- Consider Refinancing (If Rates Drop): If interest rates dip before you sell, refinancing could lower your monthly payments, making your home more attractive to buyers or improving your financial position if you decide to hold.
- Understand Your Local Market’s Supply: If inventory in your area is rising, it might be an indication to act sooner rather than later if you need to sell.
For Real Estate Investors: Prudent Opportunities
- Identify Undervalued Markets: A correction can create opportunities in markets that were previously overheated. Look for areas with strong long-term growth potential and improving fundamentals.
- Focus on Cash Flow: In an uncertain market, properties with strong rental income potential become even more attractive.
- Long-Term Perspective: Real estate is often a long-term investment. While short-term corrections can be unsettling, focus on the long-term appreciation potential and demographic trends.
- Diversify Your Portfolio: Don’t put all your eggs in one basket. Consider different property types (residential, commercial, multi-family) and geographical locations.
- Stay Liquid: Ensure you have sufficient cash reserves to weather any downturns or seize new opportunities that arise from a market correction.
Beyond the Correction: Long-Term Outlook for the US Housing Market 2026 and Beyond
While the potential 7% price correction by Q3 2026 is a significant short-term forecast, it’s equally important to consider the long-term outlook for the US Housing Market 2026 and the years following. Real estate cycles are natural, and corrections are often a healthy part of a sustainable market. After a period of rapid appreciation, a cooling-off period allows wages and incomes to catch up, improving affordability in the long run.
Demographic Tailwinds
Despite short-term fluctuations, strong demographic tailwinds continue to support the housing market. The large millennial generation is still in its prime home-buying years, and Gen Z is beginning to enter the market. These generations represent a substantial pool of future homeowners, ensuring sustained demand over the next decade. Furthermore, immigration continues to add to the population, contributing to housing needs.
Continued Supply Constraints
Even with increased construction, the underlying housing supply deficit in the U.S. is a deeply entrenched issue that will take years, if not decades, to fully resolve. Zoning restrictions, labor shortages, and high material costs continue to impede rapid expansion of new housing. This structural undersupply will likely provide a floor for prices in the long term, preventing a sustained, severe downturn.
Innovation in Housing
The housing industry is also seeing innovations in construction techniques, such as modular and prefabricated homes, which could eventually help address affordability and supply issues. While these solutions may not have a massive impact by 2026, their growing adoption could influence the market in the latter half of the decade.
Inflation and Economic Growth
The long-term health of the housing market is tied to sustained economic growth and manageable inflation. If the Federal Reserve successfully navigates a ‘soft landing’ – bringing down inflation without triggering a deep recession – the economic environment for housing could stabilize and improve post-2026. A strong economy supports job growth, wage increases, and consumer confidence, all of which are beneficial for real estate.
Conclusion: Navigating the Future of the US Housing Market 2026
The US Housing Market 2026 is poised for a period of adjustment, with expert predictions pointing towards a potential 7% price correction by Q3. This forecast is a confluence of rising interest rates, evolving supply-demand dynamics, and broader economic uncertainties. While such a correction might sound alarming, it is often a necessary recalibration after periods of rapid growth, potentially creating new opportunities for buyers and a more sustainable market in the long run.
For individuals and investors, the key to navigating this evolving landscape lies in staying informed, understanding local market nuances, and adopting a strategic, long-term perspective. Whether you are looking to buy your first home, sell an existing property, or expand your investment portfolio, diligent research and prudent decision-making will be your most valuable assets. The future of the US housing market is complex, but with the right insights, you can position yourself for success.
Author