Mastering Daily Spending Habits: Strategies for a 10% Better Outcome in 2026
Anúncios
In an increasingly complex economic landscape, understanding and mastering your daily spending habits is not just a recommendation; it’s a necessity. For many, the idea of improving financial outcomes by a significant margin, say 10%, might seem daunting. However, with strategic planning, consistent effort, and a keen awareness of where your money goes, achieving this goal by 2026 is entirely within reach. This comprehensive guide will delve into actionable strategies, psychological insights, and practical tools to help you transform your financial future. We’ll explore how small, consistent changes in your daily spending habits can accumulate into substantial savings and improved financial health over time.
Anúncios
The Foundation: Understanding Your Current Daily Spending Habits
Before you can improve your daily spending habits, you must first understand them. Many people operate on autopilot, swiping cards or making purchases without a clear picture of their overall financial flow. The first step towards a 10% better financial outcome in 2026 is a thorough audit of your current spending. This involves more than just glancing at your bank statements; it requires a deep dive into every transaction, no matter how small.
Tracking Every Penny: The Essential First Step
The most effective way to understand your daily spending habits is to track every single expense for at least one month, ideally two or three. This can be done manually with a notebook, using a spreadsheet, or with one of the many budgeting apps available. The goal here is not to judge, but to observe. Where is your money truly going? You might be surprised to find how much accumulates from seemingly insignificant purchases like daily coffees, subscription services you rarely use, or impulse buys.
Anúncios
- Manual Tracking: Keep a small notebook or use a dedicated expense journal. Write down every purchase, its cost, and the category.
- Spreadsheet Tracking: Create a simple spreadsheet with columns for date, item, cost, and category. This allows for easy summation and analysis.
- Budgeting Apps: Apps like Mint, YNAB (You Need A Budget), Personal Capital, or PocketGuard can automate much of this process by linking to your bank accounts and categorizing transactions. These tools provide real-time insights into your daily spending habits.
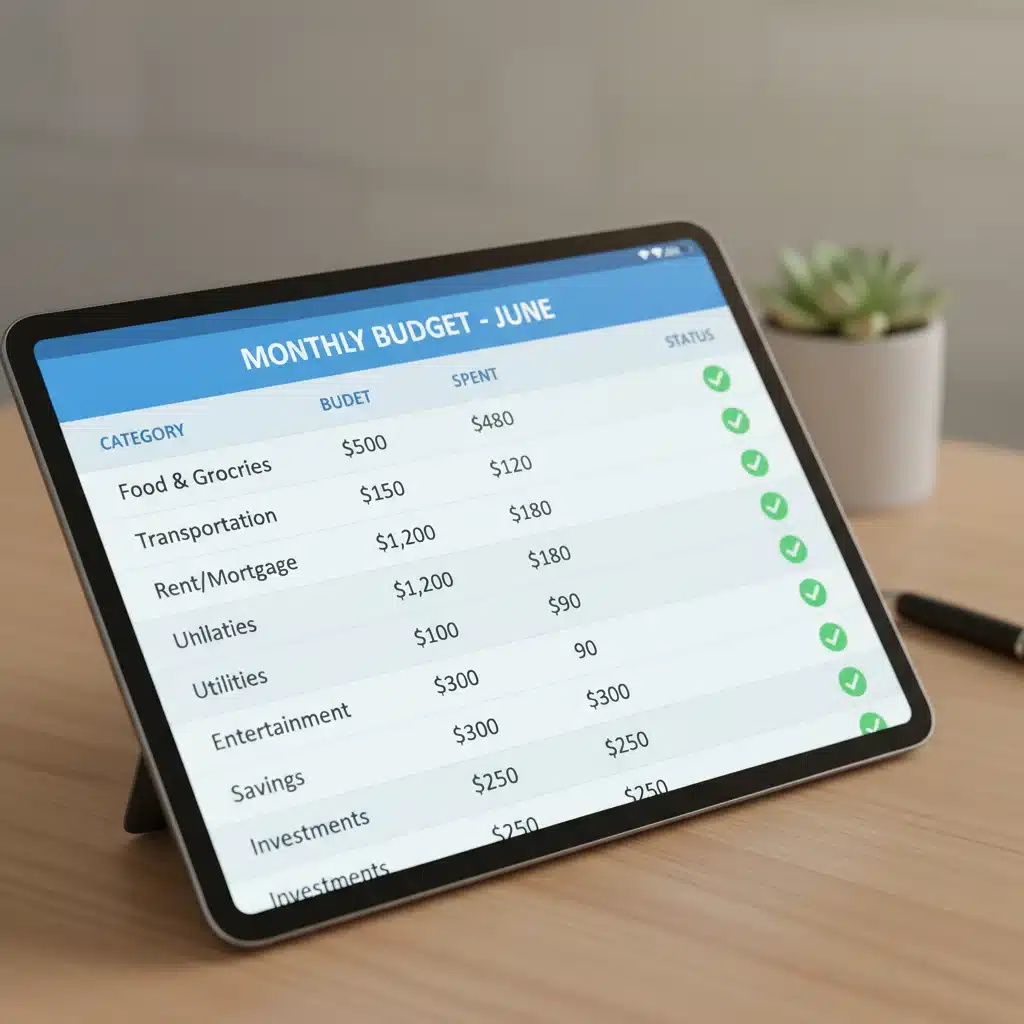
Once you have a clear picture, categorize your expenses. Common categories include housing, transportation, food (groceries and dining out), utilities, entertainment, personal care, and miscellaneous. This categorization will reveal patterns and highlight areas where you might be overspending without realizing it.
Setting Clear Financial Goals for a 10% Improvement
A 10% improvement in your financial outcome by 2026 is a concrete goal, but it needs to be broken down into smaller, manageable targets. This could mean reducing your monthly expenses by a certain percentage, increasing your savings rate, or paying down debt more aggressively. Defining what ‘10% better’ means for your specific situation is crucial.
Defining Your 10% Target
If your current monthly spending is $3,000, a 10% reduction means cutting $300 from your expenses. If your goal is to increase savings, and you currently save $500 per month, a 10% increase would mean saving an additional $50 per month. Be specific and realistic. The more defined your goals are, the easier it will be to adjust your daily spending habits to meet them.
SMART Goals for Financial Success
Apply the SMART framework to your financial goals:
- Specific: Instead of “spend less,” aim for “reduce dining out expenses by $100 per month.”
- Measurable: You need quantifiable metrics to track progress.
- Achievable: Set goals that are challenging but not impossible. A 10% improvement is often very achievable with focused effort.
- Relevant: Ensure your goals align with your broader financial aspirations.
- Time-bound: The deadline of 2026 provides a clear timeframe for your efforts.
Strategic Adjustments to Daily Spending Habits
With a clear understanding of your current spending and well-defined goals, it’s time to implement strategies to modify your daily spending habits. These strategies range from practical budgeting techniques to psychological approaches that help you make more mindful financial decisions.
The Power of Budgeting: Your Financial Roadmap
A budget is not about restriction; it’s about allocation. It’s a plan for your money that ensures your spending aligns with your values and goals. Several budgeting methods can help you manage your daily spending habits effectively:
The 50/30/20 Rule
This popular rule suggests allocating 50% of your income to needs (housing, utilities, groceries, transportation), 30% to wants (dining out, entertainment, hobbies), and 20% to savings and debt repayment. This simple framework can be a powerful guide for managing your daily spending habits and identifying areas for adjustment to achieve that 10% improvement.
Zero-Based Budgeting
With zero-based budgeting, every dollar of your income is assigned a job. This means your income minus your expenses (and savings/debt payments) should equal zero. This method requires more discipline but offers a granular level of control over your daily spending habits, making it easier to find that 10% improvement.
Envelope System (Cash Budgeting)
For those who struggle with overspending on certain categories, the envelope system can be highly effective. Allocate a specific amount of cash to different expense categories (e.g., groceries, entertainment) and place it in physical envelopes. Once an envelope is empty, you stop spending in that category until the next budgeting period. This tangible approach can dramatically alter impulse daily spending habits.
Mindful Consumption: A Shift in Perspective
Beyond strict budgeting, a fundamental shift in your approach to consumption can significantly impact your daily spending habits. Mindful consumption encourages you to think critically before every purchase, asking questions like: Do I truly need this? Can I borrow or repurpose something instead? Will this purchase bring lasting value?
Delaying Gratification
One of the most powerful psychological tools to combat impulse spending is delaying gratification. When you feel the urge to buy something non-essential, implement a 24-hour or 48-hour rule. Often, the desire passes, and you realize the purchase wasn’t necessary. This simple practice can reframe your daily spending habits from reactive to proactive.
Distinguishing Needs from Wants
It’s easy for wants to masquerade as needs. A critical exercise is to list out your expenses and honestly categorize them. While a roof over your head is a need, a premium cable package might be a want. By clearly defining these, you can consciously reduce spending on wants to free up funds for savings or debt repayment, thereby improving your daily spending habits.
Leveraging Technology for Smarter Spending
In the digital age, numerous tools and technologies can assist you in refining your daily spending habits. From automated savings apps to comparison shopping platforms, technology can be a powerful ally in achieving your 10% financial improvement.
Automated Savings and Investing
One of the easiest ways to improve your financial outcome is to automate your savings. Set up automatic transfers from your checking account to your savings or investment accounts immediately after payday. Even small, consistent contributions add up significantly over time. Apps like Acorns or Betterment can round up your purchases and invest the difference, subtly boosting your savings without requiring conscious effort in your daily spending habits.
Comparison Shopping and Deal Finding
Before making any significant purchase, take the time to compare prices. Websites and browser extensions like Honey, CamelCamelCamel, or Google Shopping can help you find the best deals, coupons, and price history. Even for groceries, planning meals and checking weekly ads can lead to substantial savings, directly impacting your daily spending habits.
Subscription Management Services
Many people unknowingly pay for subscription services they no longer use. Apps like Trim or Truebill can identify and help you cancel unwanted subscriptions, saving you money each month. This is a quick win to optimize your daily spending habits.
Optimizing Key Spending Categories
Let’s break down some common spending categories and explore specific strategies to trim costs and improve your daily spending habits.
Food: Groceries vs. Dining Out
Food is often one of the largest variable expenses. To achieve a 10% improvement:
- Meal Planning: Plan your meals for the week, create a grocery list, and stick to it. This reduces impulse buys and food waste.
- Cooking at Home: Eating out frequently is expensive. Cooking at home is almost always cheaper and often healthier.
- Packing Lunch: Bringing lunch to work or school can save hundreds of dollars a month compared to buying it daily.
- Smart Grocery Shopping: Buy in bulk for non-perishables, look for sales, and avoid shopping when hungry.
Transportation Costs
Depending on your location, transportation can be a significant expense. Consider:
- Public Transport/Carpooling: If feasible, these can drastically cut fuel and maintenance costs.
- Biking/Walking: For shorter distances, this is not only free but also beneficial for your health.
- Optimizing Car Use: Combine errands, ensure proper tire inflation, and regular maintenance to improve fuel efficiency.
- Reviewing Insurance: Shop around for better car insurance rates periodically.
Entertainment and Leisure
This category often offers the most flexibility for reducing your daily spending habits without feeling deprived:
- Free/Low-Cost Activities: Explore free local events, parks, libraries, or host potlucks instead of dining out.
- Subscription Audit: As mentioned, regularly review and cancel unused streaming services, gym memberships, or app subscriptions.
- DIY Entertainment: Movie nights at home, board games, or learning a new skill can be far cheaper than going out.
Behavioral Economics and Your Daily Spending Habits
Understanding the psychology behind your spending can be just as powerful as any budgeting tool. Behavioral economics sheds light on why we make certain financial decisions, often irrationally.
The Pain of Paying
Studies show that people feel more ‘pain’ when paying with cash than with credit cards. This is because cash is tangible, and its departure is more visceral. While using cash for all transactions might not be practical, being aware of this psychological effect can make you more mindful when using cards, thus influencing your daily spending habits positively.
Anchoring and Framing
Retailers often use anchoring (setting an initial price point to influence perception) and framing (presenting information in a way that sways decisions) to encourage spending. By recognizing these tactics, you can make more objective decisions and avoid being swayed into unnecessary purchases, improving your daily spending habits.
The Power of Habit Stacking
To establish new, positive daily spending habits, try habit stacking. Pair a new desired behavior with an existing habit. For example, every time you check your phone in the morning (existing habit), review your budget app for 5 minutes (new habit). This makes new behaviors easier to adopt and stick with.
Staying Motivated and Tracking Progress Towards 2026
Transforming your daily spending habits is a marathon, not a sprint. Maintaining motivation and consistently tracking your progress are crucial for reaching your 10% improvement goal by 2026.
Regular Financial Reviews
Schedule weekly or monthly financial check-ins. Review your budget, track your spending against your targets, and assess your progress towards your 10% goal. This allows you to make adjustments as needed and celebrate small victories. Seeing your savings grow or debt shrink is a powerful motivator.
Visualizing Your Goals
Create a visual reminder of your financial goals. This could be a thermometer chart tracking your savings, a picture of something you’re saving for (like a down payment or vacation), or a simple tally of your debt reduction. Visual cues reinforce your commitment and keep your daily spending habits aligned with your aspirations.
Rewarding Milestones (Responsibly)
As you hit smaller milestones, reward yourself, but do so responsibly. Instead of splurging on a large purchase, perhaps enjoy a nice meal out within your budget, or invest in an experience rather than a material item. These small rewards can prevent burnout and keep you engaged in the process of refining your daily spending habits.
Overcoming Common Challenges
The journey to better daily spending habits isn’t without its hurdles. Be prepared for common challenges and develop strategies to overcome them.
Unexpected Expenses
Life happens, and unexpected expenses can derail even the best-laid plans. Build an emergency fund to cover these costs without dipping into your regular budget or incurring debt. This fund acts as a buffer, protecting your progress.
Peer Pressure and Social Spending
Social situations can often lead to overspending. Learn to say no politely or suggest alternative, budget-friendly activities. Communicate your financial goals to close friends and family; they might even be inspired to join you on your journey to better daily spending habits.
Emotional Spending
Many people turn to shopping or dining out as a coping mechanism for stress, boredom, or sadness. Identify your emotional triggers and find healthier, non-financial ways to address them, such as exercise, meditation, or hobbies. Recognizing and addressing emotional spending is crucial for sustainable improvement in your daily spending habits.
The Long-Term Impact of Improved Daily Spending Habits
Achieving a 10% better financial outcome by 2026 is not just about the numbers; it’s about building sustainable habits that will benefit you for years to come. The discipline and awareness you cultivate in managing your daily spending habits will translate into greater financial security, reduced stress, and increased opportunities.
Building Wealth and Financial Freedom
Every dollar saved and every debt paid off contributes to your long-term wealth. By consistently optimizing your daily spending habits, you free up capital that can be invested, allowing compound interest to work its magic and accelerate your journey towards financial freedom.
Reduced Financial Stress
Money is a leading cause of stress for many. By taking control of your daily spending habits, you gain a sense of empowerment and reduce the anxiety associated with financial uncertainty. Knowing where your money is going and having a plan provides immense peace of mind.
Greater Flexibility and Opportunities
A stronger financial position opens doors. Whether it’s the ability to take career risks, pursue educational opportunities, travel, or simply have a larger safety net, improved daily spending habits provide the flexibility to pursue a life aligned with your values and aspirations.
Conclusion: Your Path to a 10% Better Financial Future by 2026
The journey to enhancing your daily spending habits and achieving a 10% better financial outcome by 2026 is a rewarding one. It requires introspection, commitment, and a willingness to adapt. By meticulously tracking your expenses, setting clear SMART goals, adopting effective budgeting methods, practicing mindful consumption, and leveraging modern technology, you can systematically transform your financial landscape.
Remember, small, consistent changes are often more powerful than drastic, unsustainable overhauls. Start today by understanding where your money goes, make conscious decisions about where you want it to go, and stay persistent. The financial clarity and empowerment you gain will not only lead to a 10% improvement by 2026 but will also lay the groundwork for a lifetime of sound financial health. Your future self will thank you for mastering your daily spending habits.
Author