Important Tax Law Changes for 2026: A Comprehensive Guide for U.S. Taxpayers to Maximize Returns (PRACTICAL SOLUTIONS)
As the calendar pages turn, U.S. taxpayers are once again faced with the perennial task of understanding and adapting to evolving tax legislation. The year 2026 is poised to bring forth a series of significant Tax Law Changes 2026 that could profoundly impact individuals, families, and businesses across the nation. Staying informed is not just about compliance; it’s about strategic financial planning and ensuring you maximize your returns while minimizing your tax liabilities. This comprehensive guide aims to demystify these impending changes, offering practical solutions and actionable advice to help you navigate the complex landscape ahead.
Anúncios
The tax code is a dynamic entity, constantly molded by economic shifts, political agendas, and societal needs. While the full scope of all potential alterations may not be entirely clear until closer to the date, several key areas are already under scrutiny, and proactive preparation is paramount. From potential adjustments to individual income tax rates and deductions to changes impacting business taxation and estate planning, the ripple effects of these Tax Law Changes 2026 will be felt far and wide. Our goal is to provide a clear, concise, and actionable roadmap for U.S. taxpayers to not only understand these changes but to leverage them to their financial advantage.
Understanding the Sunset Provisions of the TCJA
One of the most significant drivers of the impending Tax Law Changes 2026 stems from the expiration of several key provisions of the Tax Cuts and Jobs Act (TCJA) of 2017. Many of the individual income tax provisions enacted under the TCJA were temporary and are set to ‘sunset’ at the end of 2025, reverting to pre-TCJA law unless Congress acts to extend or modify them. This includes a broad spectrum of changes that will affect millions of taxpayers.
Anúncios
Specifically, the individual income tax rates are expected to revert to higher levels. For instance, the current 10%, 12%, 22%, 24%, 32%, 35%, and 37% brackets are projected to return to 10%, 15%, 25%, 28%, 33%, 35%, and 39.6%, respectively. This means that many taxpayers could see a direct increase in their tax burden, even if their income remains constant. Furthermore, the standard deduction, which was significantly increased under the TCJA, is also slated to decrease. This could push more taxpayers back into itemizing deductions, a process that many had moved away from due to the higher standard deduction.
Beyond rates and the standard deduction, other crucial elements affected by the sunset provisions include the child tax credit, which is expected to revert to its pre-TCJA amount and phase-out thresholds. The deduction for state and local taxes (SALT), currently capped at $10,000, may also see its limitation removed, potentially offering significant relief to taxpayers in high-tax states. The elimination of miscellaneous itemized deductions and the suspension of personal exemptions are also set to expire, bringing back these considerations into the tax planning fold. Understanding these baseline shifts is the first critical step in preparing for the Tax Law Changes 2026.
Key Areas of Impact for Individuals and Families
The Tax Law Changes 2026 will undoubtedly have a profound impact on individual and family finances. Beyond the general income tax rates and standard deduction, several specific areas warrant close attention:
Individual Income Tax Rates and Brackets
As mentioned, the most direct impact will be on the marginal tax rates. Taxpayers should review their income projections for 2026 and beyond to anticipate how these higher rates might affect their take-home pay and overall financial planning. This might be an opportune time to consider strategies such as Roth conversions, accelerating income into 2025, or deferring deductions into 2026, depending on individual circumstances and projected tax brackets.
Standard Deduction vs. Itemized Deductions
With the standard deduction potentially decreasing, more taxpayers may find themselves itemizing deductions again. This necessitates meticulous record-keeping for eligible expenses such as mortgage interest, charitable contributions, medical expenses (if they exceed the adjusted gross income threshold), and potentially, state and local taxes if the SALT cap is indeed lifted. Taxpayers who previously stopped itemizing should begin tracking these expenses diligently in anticipation of these Tax Law Changes 2026.
Child Tax Credit and Other Family Credits
The child tax credit’s potential reduction and stricter phase-out rules could significantly impact families with children. It’s crucial for parents to understand the pre-TCJA rules that may come back into effect and adjust their financial planning accordingly. This might include re-evaluating childcare expenses, college savings plans, and overall budget allocations. Other family-related credits may also revert, requiring a thorough review of eligibility criteria.
Estate and Gift Taxes
Another critical area affected by the sunset provisions is estate and gift tax exemptions. The current historically high exemption amounts are scheduled to be cut roughly in half. This change will have significant implications for high-net-worth individuals and families engaged in estate planning. Those considering large gifts or comprehensive estate planning strategies should consult with an estate planning attorney and tax advisor well before the end of 2025 to potentially utilize the higher exemptions while they are still available. Proactive planning in this area can save millions in future estate taxes.
Implications for Businesses and Self-Employed Individuals
While many of the TCJA’s corporate tax cuts were made permanent, several provisions impacting pass-through entities and self-employed individuals are also set to expire, creating significant Tax Law Changes 2026 for businesses.
Qualified Business Income (QBI) Deduction (Section 199A)
The 20% Qualified Business Income (QBI) deduction for owners of pass-through entities (such as sole proprietorships, partnerships, and S corporations) is also scheduled to expire at the end of 2025. This deduction has provided substantial tax savings for many small business owners and self-employed individuals. Its expiration would mean a considerable increase in taxable income for these entities. Businesses should begin assessing how the loss of this deduction will impact their bottom line and explore alternative strategies to mitigate the increased tax burden. This could involve re-evaluating business structures, adjusting compensation strategies, or exploring other available deductions and credits.
Bonus Depreciation and Section 179 Expensing
While not directly tied to the TCJA sunset, the phase-down of bonus depreciation provisions is also a significant factor for businesses. Bonus depreciation, which allows businesses to immediately deduct a large percentage of the cost of eligible property, is already phasing down. It was 100% for property placed in service before 2023, then 80% for 2023, 60% for 2024, 40% for 2025, and will be 20% for 2026, before expiring in 2027. This gradual reduction means that businesses planning significant capital expenditures in 2026 should factor in a lower immediate deduction compared to previous years. Similarly, Section 179 expensing limits are adjusted annually, and while generally generous, businesses should monitor these limits for any changes that might affect their ability to deduct equipment purchases.
Interest Expense Limitation (Section 163(j))
The limitation on business interest expense deductions under Section 163(j) also saw a change for tax years beginning after December 31, 2021. The deduction was limited to 30% of adjusted taxable income (ATI), with ATI initially calculated without regard to depreciation, amortization, or depletion. However, for tax years beginning in 2022 and beyond, ATI *includes* depreciation and amortization, which can significantly reduce the amount of deductible interest for some businesses. While not a 2026 sunset provision, it’s an ongoing change that businesses must continue to monitor and understand, as it can impact financing decisions and overall tax liability.
Practical Solutions and Strategies for U.S. Taxpayers
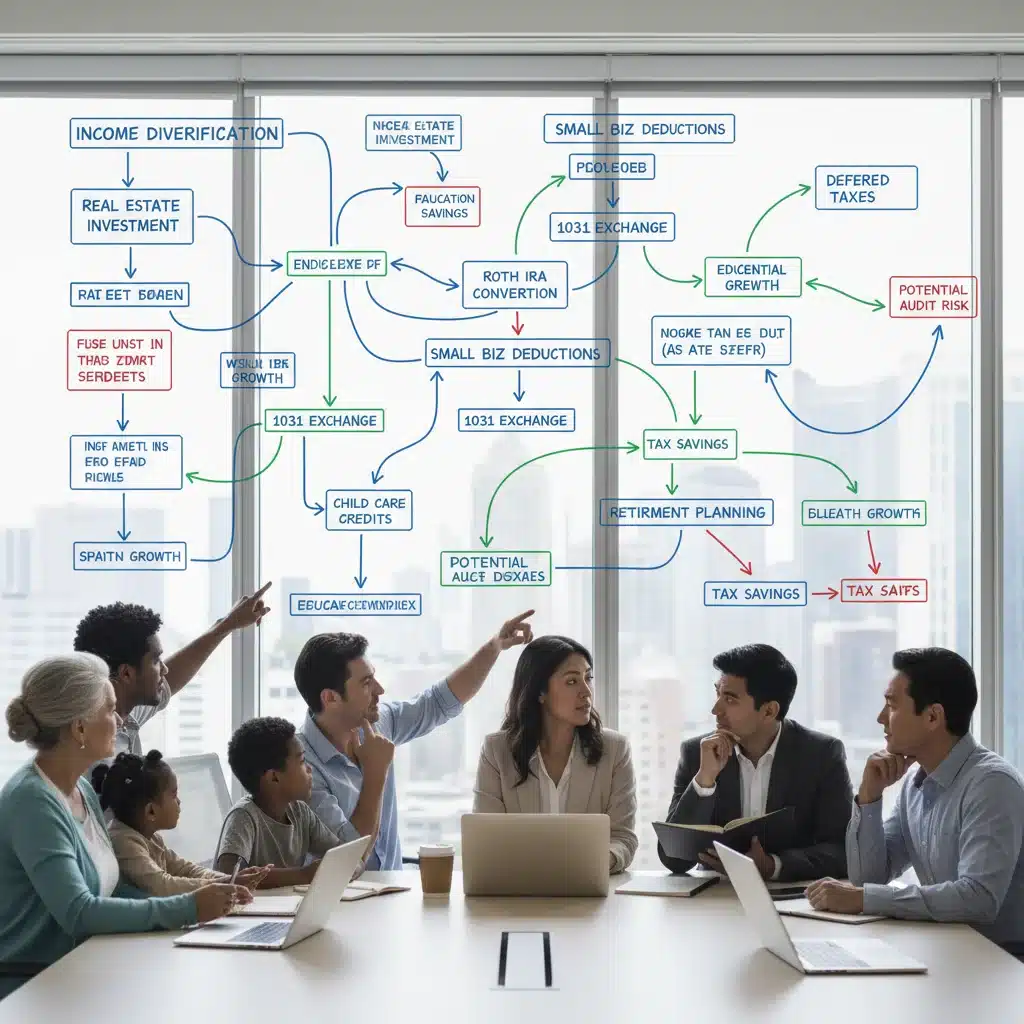
Given the anticipated Tax Law Changes 2026, proactive planning is not just advisable, it’s essential. Here are some practical solutions and strategies for individuals and businesses to consider:
1. Re-evaluate Your Withholding and Estimated Taxes
With potential changes to income tax rates and deductions, your current W-4 elections or estimated tax payments might no longer be appropriate. Review your projected income and deductions for 2026 and adjust your withholding or estimated payments to avoid underpayment penalties. Use the IRS Tax Withholding Estimator as a valuable tool.
2. Maximize Deductions and Credits Before 2026
If certain deductions or credits are set to expire or diminish, consider accelerating eligible expenses into 2025. For instance, if you anticipate a higher tax bracket in 2026, consider making larger charitable contributions or medical expenditures in 2025 if feasible and beneficial. Similarly, if the SALT cap is expected to be lifted, deferring certain state and local tax payments might be advantageous.
3. Review Investment Strategies
The changes could impact capital gains taxes, dividend tax rates, and the attractiveness of various investment vehicles. Consult with a financial advisor to review your investment portfolio and strategy. Consider tax-loss harvesting, rebalancing, or adjusting contributions to tax-advantaged accounts like 401(k)s, IRAs, and HSAs to optimize your tax position under the new rules. Roth conversions might be particularly attractive in 2025 if you anticipate being in a higher tax bracket in 2026.
4. Estate Planning Update
For those with significant assets, the potential reduction in estate and gift tax exemptions makes revisiting your estate plan critical. Consider utilizing the higher exemption amounts available through 2025 by making substantial gifts or establishing trusts. Work with an experienced estate planning attorney to ensure your plan aligns with the impending changes and your long-term goals.
5. Business Structure and Expense Management
Businesses, especially pass-through entities, should analyze the impact of the QBI deduction’s expiration. This might involve exploring alternative business structures, optimizing operational expenses, or strategically timing capital expenditures to maximize remaining bonus depreciation or Section 179 expensing in 2025. Maintain meticulous records of all business expenses to ensure you can claim every available deduction.
6. Seek Professional Tax Advice
The complexity of the Tax Law Changes 2026 makes professional guidance invaluable. A qualified tax advisor can provide personalized advice based on your unique financial situation, helping you understand the specific impacts and identify tailored strategies to optimize your tax outcome. They can help you navigate the nuances of the legislation and ensure compliance.
7. Stay Informed and Adaptable
Tax legislation is subject to ongoing debate and potential modifications. Stay updated on legislative developments and be prepared to adapt your strategies as more definitive information becomes available. Regularly check reputable tax news sources, IRS announcements, and consult with your tax professional.
Anticipated New Legislation and Potential Further Changes
While the sunset provisions of the TCJA form the bedrock of the expected Tax Law Changes 2026, it’s also crucial to acknowledge that Congress may introduce new legislation or extend existing provisions. The political landscape leading up to and following the 2024 elections will undoubtedly shape the final form of the tax code in 2026. Here are some areas where additional legislative activity could occur:
Potential Extensions of TCJA Provisions
There is always a possibility that some or all of the expiring TCJA provisions could be extended, either temporarily or permanently. Lobbying efforts from various industries and advocacy groups will be intense, pushing for extensions of favorable tax treatments. However, any extensions would likely come with political compromises, potentially introducing new complexities or offsets.
Focus on Wealth and High-Income Earners
Depending on the political climate, there could be renewed efforts to increase taxes on high-net-worth individuals and corporations. This could manifest as adjustments to capital gains rates, new wealth taxes, or modifications to existing corporate tax structures. Such changes would add another layer of complexity to financial planning for affluent taxpayers.
Climate-Related Tax Incentives
The emphasis on environmental sustainability continues to grow, and it’s plausible that new or expanded tax credits and incentives for green energy, energy efficiency, and sustainable practices could be introduced or modified. Both individuals and businesses investing in these areas should monitor potential opportunities for tax relief.
Social Program Funding
Discussions around funding for social programs, healthcare, and infrastructure could also lead to new tax proposals. These might include adjustments to payroll taxes, new excise taxes, or changes to how certain benefits are taxed. Taxpayers should be aware that broader economic and social policy goals often translate into tax code modifications.
The Importance of Digital Record-Keeping and Cybersecurity
As tax laws evolve and become increasingly complex, the importance of meticulous record-keeping cannot be overstated. With the Tax Law Changes 2026, taxpayers may find themselves needing to substantiate more deductions or provide more detailed financial information than before. Digital record-keeping offers a streamlined, efficient, and secure way to manage your financial documents.
Benefits of Digital Record-Keeping:
- Accessibility: Easily access documents from anywhere, anytime, which is crucial for remote work or consulting with tax professionals.
- Organization: Digital tools allow for easy categorization and searchability of documents, reducing the time spent on tax preparation.
- Security: Encrypted cloud storage and secure digital platforms offer better protection against physical damage or loss compared to paper records.
- Efficiency: Reduces clutter and streamlines the process of sharing information with tax preparers, leading to a more efficient tax season.
However, with increased reliance on digital platforms comes the amplified need for robust cybersecurity measures. Tax-related information is highly sensitive, making taxpayers prime targets for identity theft and fraud. Ensure that any digital platforms you use for tax preparation or record storage are reputable and employ strong encryption and multi-factor authentication. Regularly update your passwords and be vigilant against phishing scams, especially during tax season. Protecting your financial data is as crucial as understanding the tax laws themselves.
Conclusion: Navigating the Future of U.S. Taxation
The impending Tax Law Changes 2026 represent a significant juncture for U.S. taxpayers. The sunsetting of key TCJA provisions, coupled with potential new legislative actions, will undoubtedly reshape the financial landscape for individuals and businesses alike. While the specifics may continue to evolve, the core message remains clear: proactive engagement and strategic planning are paramount.
By understanding the potential shifts in individual income tax rates, standard deductions, child tax credits, and the Qualified Business Income deduction, taxpayers can begin to formulate effective strategies. Whether it involves re-evaluating investment portfolios, updating estate plans, optimizing business structures, or simply adjusting withholding, every step taken now contributes to a smoother and more financially advantageous transition into the new tax era.
Remember, the tax code is complex, and attempting to navigate these significant changes without expert assistance can lead to missed opportunities or costly errors. Engaging with a qualified tax professional is one of the most practical solutions you can employ. They can provide tailored advice, help you interpret the nuances of the law, and ensure you are maximizing every available advantage while remaining fully compliant. Stay informed, plan strategically, and secure your financial future amidst the Tax Law Changes 2026.