The financial landscape for millions of Americans who rely on Social Security and Veterans Affairs (VA) benefits is constantly evolving. A critical component of this evolution is the Cost-of-Living Adjustment, or COLA. As we look ahead, the anticipated 2026 COLA increase is already a topic of significant discussion, promising to shape the purchasing power and financial stability of retirees, disabled individuals, and veterans across the nation. Understanding what this increase means, how it’s calculated, and its potential impact is crucial for effective financial planning.
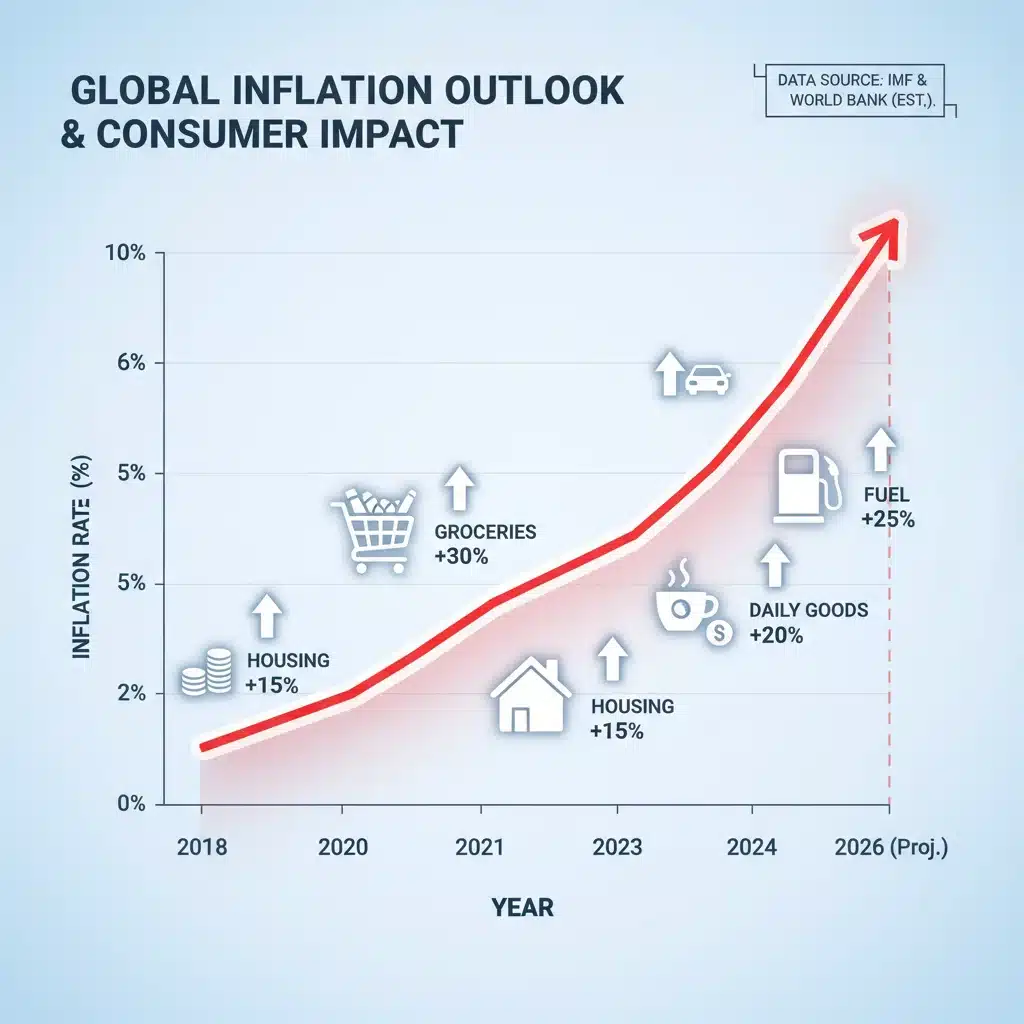
For many, Social Security and VA benefits represent a primary, if not sole, source of income. These benefits are designed to provide a safety net, but their real value can be eroded by inflation – the persistent rise in the price of goods and services. This is where COLA plays its vital role. It’s an annual adjustment intended to help beneficiaries keep pace with inflation, ensuring their benefits retain their purchasing power over time. Without COLA, the fixed income of beneficiaries would steadily diminish in real terms, making it increasingly difficult to afford necessities.
Anúncios
The 2026 COLA increase is not just a number; it’s a reflection of economic realities and a determinant of countless household budgets. It affects everything from the ability to afford groceries and utilities to healthcare costs and housing. Therefore, staying informed about the projections and understanding the mechanisms behind these adjustments is paramount for anyone receiving these benefits or those planning for their future.
The Mechanics of COLA: How It’s Determined
To truly grasp the significance of the 2026 COLA increase, it’s essential to understand how these adjustments are calculated. The Social Security Administration (SSA) is responsible for determining the COLA for Social Security benefits, while VA benefits often mirror these adjustments, though specific legislative actions can sometimes influence VA rates independently.
The primary index used for calculating the COLA for Social Security is the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). This index measures the average change over time in the prices paid by urban wage earners and clerical workers for a market basket of consumer goods and services. The COLA is specifically based on the increase in the CPI-W from the third quarter of the previous year to the third quarter of the current year. For example, the COLA announced in October 2025 for 2026 benefits would be based on the CPI-W data from July, August, and September of 2025 compared to the same period in 2024.
Anúncios
Several factors influence the CPI-W, and consequently, the COLA. These include energy prices, food costs, housing expenses, and medical care. Economic trends, global events, and domestic policies can all contribute to inflationary pressures that ultimately dictate the COLA percentage. Predicting the exact 2026 COLA increase this far out is challenging, as it depends entirely on future inflation rates. However, economists and analysts regularly provide forecasts based on current economic indicators and historical patterns.
It’s important to note that if there is no increase in the CPI-W, or if it decreases, there will be no COLA. This has happened in the past during periods of low or negative inflation. However, the current economic climate, marked by ongoing inflationary pressures, suggests that a 2026 COLA increase is highly probable, albeit the exact percentage remains speculative.
Historical Context: COLA Trends and Their Impact
Looking at past COLA adjustments can provide valuable context for understanding the potential impact of the 2026 COLA increase. Over the years, COLA percentages have varied significantly, reflecting different economic periods. For instance, in times of high inflation, such as the early 1980s, COLA increases were in the double digits. Conversely, during periods of low inflation or deflation, COLA has been minimal or even zero.
Recent years have seen more substantial COLA increases compared to the decade leading up to the pandemic. The 2022 COLA of 5.9% and the 2023 COLA of 8.7% were particularly impactful, largely driven by the surge in inflation following the COVID-19 pandemic and global supply chain disruptions. These larger adjustments provided much-needed relief to beneficiaries grappling with soaring prices for everyday goods and services.
These historical trends underscore the critical role COLA plays in maintaining the financial well-being of beneficiaries. A robust 2026 COLA increase would help offset continued inflationary pressures, while a smaller adjustment might mean beneficiaries need to stretch their budgets further. It’s a delicate balance, and the annual announcement is eagerly awaited by millions.
Projecting the 2026 COLA Increase: What Experts Are Saying
While official projections for the 2026 COLA increase are still a considerable time away, financial experts and organizations like the Committee for a Responsible Federal Budget (CRFB) and the Congressional Budget Office (CBO) regularly release economic forecasts that can hint at potential COLA figures. These forecasts consider various economic indicators, including anticipated inflation rates, wage growth, and global economic stability.
Current economic sentiment suggests that while inflation may moderate from its peak, it is likely to remain a factor. Supply chain issues, geopolitical tensions, and domestic fiscal policies can all contribute to sustained price increases. Therefore, many analysts anticipate a moderate, yet significant, 2026 COLA increase, likely falling somewhere between the very low percentages seen in the 2010s and the exceptionally high figures of 2022-2023.
It’s crucial to remember that these are projections and can change based on evolving economic data. Unexpected events, such as new global crises or significant shifts in monetary policy, could alter these forecasts dramatically. Beneficiaries should monitor reliable economic news sources and official announcements from the Social Security Administration as the time for the 2026 COLA determination approaches.
Impact on Social Security Beneficiaries
For the millions of Americans receiving Social Security benefits, the 2026 COLA increase will directly translate into a higher monthly payment. This adjustment is applied across all types of Social Security benefits, including retirement, disability (SSDI), and survivor benefits. The primary goal is to ensure that the purchasing power of these benefits is not eroded by inflation, allowing beneficiaries to maintain their standard of living.
A significant COLA can have a profound positive effect. It can mean more disposable income for essentials like food, housing, and healthcare, or even allow for small discretionary spending. Conversely, a lower-than-expected COLA, especially if inflation remains high, can put a strain on household budgets, forcing beneficiaries to make difficult choices about their expenditures.
Beyond the immediate increase in monthly payments, the 2026 COLA increase also has long-term implications. Each COLA adjustment becomes part of the base benefit amount for subsequent years. This compounding effect means that consistent COLA increases over time are crucial for the sustained financial health of beneficiaries throughout their retirement or period of disability.
Navigating Healthcare Costs with COLA
One of the most significant expenditures for many Social Security beneficiaries is healthcare. Medicare Part B premiums, which are often deducted directly from Social Security checks, can also be affected by COLA. While a higher COLA means a larger benefit check, it doesn’t always guarantee a net increase in take-home pay if Medicare premiums rise commensurately or even more steeply. This phenomenon, sometimes referred to as the ‘hold harmless’ provision, ensures that most beneficiaries’ net Social Security payment doesn’t decrease due to rising Medicare premiums.
However, for higher-income beneficiaries who pay Income-Related Monthly Adjustment Amounts (IRMAA) for Medicare Parts B and D, or for new beneficiaries, the interaction between COLA and Medicare premiums can be more complex. Understanding this relationship is vital for comprehensive financial planning, especially when anticipating the 2026 COLA increase.
Implications for VA Benefits Recipients
Veterans who receive disability compensation, pension, or other benefits from the Department of Veterans Affairs also typically see adjustments tied to the Social Security COLA. Historically, Congress has authorized COLA increases for VA benefits that match the Social Security COLA percentage. This ensures that veterans’ benefits also keep pace with the rising cost of living.
The 2026 COLA increase will therefore be just as critical for veterans as it is for Social Security recipients. It will impact the monthly compensation received by veterans for service-connected disabilities, as well as pension benefits for low-income wartime veterans and their survivors. For many veterans and their families, these benefits are a lifeline, providing crucial support for daily living expenses, medical care, and other necessities.
A robust COLA can significantly enhance the financial stability of veterans, allowing them to better manage their finances without the constant worry of inflation eroding their purchasing power. This is particularly important for veterans with severe disabilities who may have limited employment opportunities or significant ongoing medical expenses.
Advocacy for Veterans and COLA
Veterans’ advocacy groups play a crucial role in ensuring that COLA adjustments are applied fairly and effectively to VA benefits. They continuously monitor economic conditions and legislative developments to advocate for timely and adequate increases. The expectation is that the 2026 COLA increase for VA benefits will align with the Social Security COLA, continuing the tradition of parity.
However, it’s always prudent for veterans to stay informed through official VA channels and reputable veterans’ organizations. Any specific legislative actions related to VA benefits can sometimes introduce nuances that might affect how the COLA is applied or if additional adjustments are made.
Financial Planning in Light of the 2026 COLA Increase
Whether you are a current beneficiary or planning for future benefits, incorporating the anticipated 2026 COLA increase into your financial planning is a smart move. While the exact percentage is unknown, understanding the mechanism and potential range can help you make more informed decisions.
For Current Beneficiaries:
- Budget Adjustment: Once the 2026 COLA is announced, adjust your monthly budget to reflect the new income. This is an opportunity to re-evaluate spending and ensure your budget aligns with your financial goals.
- Review Healthcare Costs: Pay close attention to how the COLA interacts with Medicare premiums and other healthcare expenses. Factor in any potential increases in these costs when assessing your net benefit.
- Emergency Savings: Even with COLA, maintaining an emergency fund is crucial. A COLA helps with inflation, but unexpected expenses can still arise.
- Debt Management: If you have outstanding debts, consider how the increased income might allow you to accelerate repayment or reduce interest accrual.
For Future Beneficiaries and Planners:
- Retirement Projections: When calculating your future retirement income, factor in potential COLA adjustments. While you shouldn’t rely solely on COLA to significantly boost your income, it’s an important component to consider for maintaining purchasing power.
- Diversify Income Streams: While Social Security and VA benefits are vital, aim for diversified income streams in retirement to provide greater financial security and flexibility, regardless of COLA fluctuations.
- Stay Informed: Keep abreast of economic forecasts and official announcements regarding COLA. This knowledge can help you make timely adjustments to your long-term financial plans.
- Consult a Financial Advisor: A financial advisor specializing in retirement planning can provide personalized guidance on how COLA and other factors will affect your specific situation, helping you optimize your financial strategy.
The Broader Economic Picture and Future COLA Challenges
The 2026 COLA increase doesn’t exist in a vacuum; it’s intricately linked to the broader economic health of the nation. Factors such as employment rates, wage growth, global trade, and government spending all play a role in shaping inflation and, by extension, future COLA adjustments. A robust economy with stable growth and controlled inflation generally leads to more predictable and beneficial COLA outcomes.
However, the Social Security system also faces long-term solvency challenges. The ratio of workers paying into the system to beneficiaries drawing from it is declining. While COLA is essential for beneficiaries, its determination must also consider the fiscal health of the Social Security trust funds. Discussions about potential reforms to Social Security often touch upon the COLA calculation method, with some advocating for alternative inflation indexes, such as the Consumer Price Index for the Elderly (CPI-E), which proponents argue better reflects the spending patterns of seniors.
Any changes to the COLA calculation method would have significant implications for future beneficiaries and would undoubtedly be subject to extensive debate. For now, the CPI-W remains the standard, and the 2026 COLA increase will be determined based on its movements.
Conclusion: Preparing for the 2026 COLA Increase
The anticipated 2026 COLA increase is more than just an annual adjustment; it’s a critical mechanism designed to protect the financial stability of millions of Americans. For Social Security beneficiaries and veterans receiving VA benefits, this adjustment directly influences their ability to afford essential goods and services in an ever-changing economic environment.
While the exact percentage of the 2026 COLA increase remains to be seen, staying informed about economic trends, understanding the calculation methodology, and proactively planning your finances are the best strategies. By doing so, you can better prepare for the financial realities of 2026 and beyond, ensuring that your benefits continue to provide the support you need to maintain your quality of life.
As the official announcement approaches, typically in October of the preceding year, beneficiaries should pay close attention to updates from the Social Security Administration and the Department of Veterans Affairs. This foresight will empower you to make timely and informed decisions, safeguarding your financial future against the ebb and flow of inflation and the cost of living.