The 2026 Public Service Loan Forgiveness (PSLF) Program: Updated Eligibility and Application Tips
For many dedicated individuals pursuing careers in public service, the promise of student loan forgiveness is a beacon of hope. The Public Service Loan Forgiveness (PSLF) program, designed to alleviate the financial burden on those who commit to serving their communities, has undergone various changes since its inception. As we approach 2026, understanding the latest updates to the PSLF program is crucial for current and aspiring public servants. This comprehensive guide will delve into the nuances of the PSLF 2026 updates, offering clarity on eligibility, application procedures, and essential tips to ensure you are well-positioned for loan forgiveness.
The journey to student loan forgiveness can often feel complex, but with the right information, it becomes a navigable path. The PSLF program, while incredibly beneficial, requires meticulous attention to detail regarding employment, loan types, and repayment plans. Our aim is to demystify the PSLF 2026 updates, providing you with a clear roadmap to successfully achieve your financial goals while continuing your invaluable work in public service.
Anúncios
Understanding the Core of PSLF: A Quick Recap
Before we dive into the specifics of the PSLF 2026 updates, let’s briefly revisit the foundational principles of the Public Service Loan Forgiveness program. Established in 2007, PSLF aims to encourage individuals to enter and remain in full-time public service employment. The program promises to forgive the remaining balance on Direct Loans after 120 qualifying monthly payments have been made under a qualifying repayment plan while working full-time for a qualifying employer.
Key components include:
Anúncios
- Qualifying Employment: Working for a U.S. federal, state, local, or tribal government agency (this includes military service), or a not-for-profit organization that is tax-exempt under Section 501(c)(3) of the Internal Revenue Code.
- Qualifying Loans: Only Direct Loans are eligible. Other federal loan types (FFEL, Perkins) must be consolidated into a Direct Consolidation Loan to qualify.
- Qualifying Repayment Plans: Income-Driven Repayment (IDR) plans are typically the most common and beneficial, though the Standard Repayment Plan also qualifies.
- Qualifying Payments: 120 on-time, full monthly payments made after October 1, 2007, while employed full-time by a qualifying employer under a qualifying repayment plan.
The beauty of PSLF lies in its direct approach to rewarding public service. However, its strict requirements have historically led to confusion and frustration for many applicants. The PSLF 2026 updates seek to refine these processes and potentially expand access, making it more critical than ever to stay informed.
The Landscape of PSLF: Anticipated 2026 Changes
While definitive changes for 2026 are still being shaped by legislative discussions and departmental policy adjustments, several trends and proposed reforms indicate the direction of the PSLF 2026 updates. These updates are often a response to feedback from borrowers, administrative challenges, and broader economic considerations.
Potential Streamlining of Eligibility Criteria
One of the most significant areas of focus for future PSLF reforms is the simplification of eligibility criteria. Historically, many borrowers found themselves disqualified due to technicalities, such as having the wrong loan type or being on a non-qualifying repayment plan for a period. The Department of Education has been working towards making the program more accessible and forgiving for those who genuinely meet the spirit of the law.
- Expanded Definition of Full-Time Employment: There might be adjustments to how ‘full-time’ employment is defined, potentially offering more flexibility for those working multiple part-time qualifying jobs that collectively meet the full-time threshold.
- Inclusion of Previously Excluded Payments: Efforts to count certain periods of deferment or forbearance, or even payments made under non-qualifying plans, have been a recurring theme in recent waivers. While the Temporary Expanded PSLF (TEPSLF) addressed some of these, ongoing discussions suggest a more permanent integration of flexible payment counting.
- Clarification on Employer Type: While the core definition of qualifying employers is unlikely to change drastically, there may be clearer guidelines or a more streamlined process for employers to confirm their qualifying status, reducing ambiguity for borrowers.
These potential shifts in the PSLF 2026 updates aim to reduce the administrative burden on borrowers and ensure that dedicated public servants are not unfairly excluded from the forgiveness they’ve earned.
Navigating the Application Process for PSLF in 2026
The application process for PSLF has seen considerable evolution, moving from a complex, often opaque system to a more user-friendly online tool. As we look towards 2026, further refinements are expected to make the process even smoother.
The PSLF Help Tool: Your Best Friend
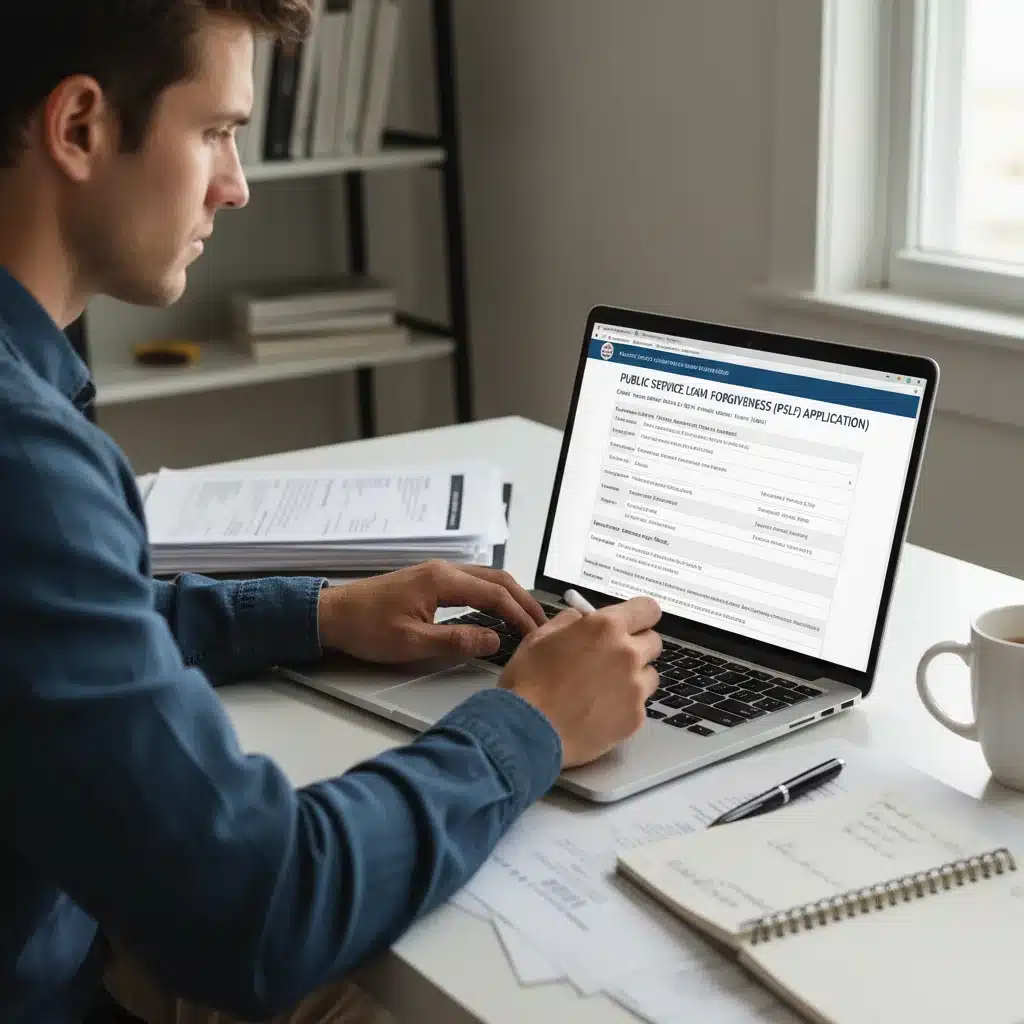
The PSLF Help Tool, available on the Federal Student Aid (FSA) website, is an invaluable resource. It helps borrowers determine if their employer qualifies, if their loans are eligible, and generate the necessary Employment Certification Form (ECF). Regular submission of the ECF is critical for tracking progress towards the 120 qualifying payments.
For the PSLF 2026 updates, anticipate:
- Enhanced User Interface: A more intuitive and guided experience within the Help Tool, potentially with automated checks or prompts to reduce common errors.
- Improved Communication: More transparent and proactive communication from loan servicers and FSA regarding payment counts and eligibility status.
- Digital Signature Integration: Wider acceptance and easier integration of digital signatures for employer certification, speeding up the verification process.
It’s vital to submit your ECF annually, or whenever you change employers. This proactive approach helps to catch any issues early on, preventing potential heartache down the line when you apply for forgiveness.
The Forgiveness Application Itself
Once you believe you have made 120 qualifying payments, you will need to submit the PSLF Application. This typically happens after your final ECF confirms your 120th payment. The PSLF 2026 updates might introduce a more integrated application process, potentially allowing for a seamless transition from payment tracking to forgiveness application within the same online portal.
Key tips for the application:
- Verify Payment Counts: Before applying, ensure your loan servicer’s records align with your understanding of your qualifying payments. Dispute any discrepancies immediately.
- Keep Meticulous Records: Maintain copies of all submitted ECFs, payment confirmations, and correspondence with your loan servicer. This documentation is your safety net.
- Be Patient: The forgiveness application review process can take time. Continue to monitor your loan status and respond promptly to any requests for additional information.
Maximizing Your Chances: Essential Tips for PSLF Success in 2026
Beyond understanding the PSLF 2026 updates, there are evergreen strategies that will significantly improve your chances of achieving loan forgiveness. These tips are rooted in proactive management and thorough documentation.
1. Consolidate Your Loans (If Necessary)
If you have FFEL Program loans or Perkins Loans, they are not eligible for PSLF unless you consolidate them into a Direct Consolidation Loan. This is a critical first step for many borrowers. Be aware that consolidation resets your payment count to zero, but recent waivers have offered exceptions to this rule for past payments. Always check the latest guidance from FSA before consolidating, especially with potential PSLF 2026 updates.
2. Enroll in an Income-Driven Repayment (IDR) Plan
While the Standard Repayment Plan for Direct Loans also qualifies for PSLF, it is typically for a 10-year term, meaning your loans would be paid off before you reach 120 payments. IDR plans (such as SAVE, PAYE, IBR, ICR) adjust your monthly payment based on your income and family size, often resulting in lower payments and a remaining balance to be forgiven after 120 qualifying payments. This makes IDR plans the most strategic choice for PSLF participants.
3. Certify Your Employment Annually
This cannot be stressed enough. Submitting the Employment Certification Form (ECF) annually, and each time you change employers, is the best way to track your progress and ensure your employment qualifies. It allows the Department of Education and your loan servicer to confirm your eligibility and update your payment count regularly. This proactive approach helps avoid last-minute surprises when you apply for forgiveness, especially with any new procedures introduced by PSLF 2026 updates.
4. Keep Detailed Records
Maintain a personal file (digital or physical) with copies of everything related to your student loans and PSLF application. This includes:
- All submitted ECFs and PSLF Applications.
- Letters from your loan servicer.
- Proof of employment (pay stubs, W-2s).
- Records of all payments made.
- Any communication with FSA or your loan servicer.
This documentation can be invaluable if there are any discrepancies in your payment count or eligibility status.
5. Stay Informed About Program Changes
The PSLF program has been subject to various legislative and administrative changes. Subscribing to updates from the Department of Education, following reputable financial aid news sources, and regularly checking the FSA website will ensure you are aware of any new PSLF 2026 updates or temporary waivers that could impact your eligibility or payment count.
6. Understand What Counts as a Qualifying Payment
A qualifying payment is a full, on-time payment made after October 1, 2007, under a qualifying repayment plan, while employed full-time by a qualifying employer. Payments made during periods of deferment or forbearance (unless under a specific waiver) generally do not count. Understanding these nuances is key to accurately tracking your progress.
7. Be Mindful of Employment Changes
If you switch from a qualifying employer to a non-qualifying one, or vice-versa, ensure you understand how this affects your PSLF timeline. Your payments only count towards PSLF when you are employed by a qualifying organization. If you leave public service, your payments will no longer count, but your previously accumulated qualifying payments remain on record for when you return to qualifying employment.
Common Pitfalls and How to Avoid Them with PSLF 2026 Updates
Despite the program’s intent, many borrowers encounter obstacles. Being aware of these common pitfalls can help you navigate the PSLF journey more smoothly.
Incorrect Loan Types
Pitfall: Believing all federal loans qualify. Only Direct Loans are eligible. FFEL and Perkins loans must be consolidated.
Solution: Check your loan types on studentaid.gov. If you have FFEL or Perkins, consolidate them into a Direct Consolidation Loan. Be mindful of how consolidation impacts past payments and look for any PSLF 2026 updates that might offer retroactive counting for consolidated loans.
Wrong Repayment Plan
Pitfall: Making payments under a non-qualifying repayment plan (e.g., Extended Repayment Plan, Graduated Repayment Plan).
Solution: Enroll in an Income-Driven Repayment (IDR) plan. These plans are designed to make your payments affordable and are the most common path to PSLF. Review your plan annually, especially with income changes.
Failure to Submit Employment Certification Forms
Pitfall: Waiting until you think you’ve made 120 payments to submit any forms.
Solution: Submit an ECF annually and every time you change employers. This ensures your employment is verified and your payment count is updated regularly, preventing issues from compounding over time. This is perhaps the most critical administrative step for PSLF success.
Not Tracking Payments
Pitfall: Relying solely on your loan servicer’s count without cross-referencing your own records.
Solution: Keep your own detailed records of payments, employment periods, and communications. Regularly check your payment count on your servicer’s website and on studentaid.gov. Discrepancies should be addressed promptly.
Changes in Servicer
Pitfall: Losing track of records or having issues with payment counts when your loan servicer changes.
Solution: When a servicer change occurs, immediately download all your loan history and payment records from the old servicer. Confirm that the new servicer has accurate information. The PSLF 2026 updates may include better protocols for servicer transitions, but personal vigilance remains essential.
The Future of PSLF Beyond 2026
The Public Service Loan Forgiveness program has demonstrated its value in supporting crucial public sector roles. As we look beyond the immediate PSLF 2026 updates, it’s clear that the program will continue to evolve. Advocacy groups and policymakers are consistently exploring ways to make PSLF more efficient, equitable, and effective.
Potential future considerations might include:
- Broader Employer Definitions: Expanding the types of qualifying employers to include more organizations that serve the public good but may not fit the current 501(c)(3) or government agency definitions.
- Simplified Loan Structures: Moving towards a simpler federal student loan system could inherently make programs like PSLF easier to navigate, reducing the need for consolidation or specific repayment plan choices.
- Automatic Enrollment/Tracking: Implementing systems that automatically track qualifying employment and payments for borrowers, reducing the administrative burden on individuals.
While these are speculative, they reflect a broader desire to strengthen PSLF as a cornerstone of public service support. Staying engaged with legislative developments and policy proposals will be key for anyone planning their career around the benefits of PSLF.
Conclusion: Preparing for PSLF Success in 2026 and Beyond
The Public Service Loan Forgiveness program, with its upcoming PSLF 2026 updates, remains an incredibly powerful tool for public servants to manage their student loan debt. While the program requires diligence and attention to detail, the reward of loan forgiveness is well worth the effort.
By understanding the core requirements, actively engaging with the PSLF Help Tool, meticulously tracking your employment and payments, and staying informed about any new changes, you can confidently navigate your path to forgiveness. Remember, your commitment to public service is invaluable, and the PSLF program is designed to support you in that commitment.
Don’t let the complexity deter you. Break down the process into manageable steps, utilize the resources available, and maintain thorough records. With these strategies, you’ll be well-equipped to leverage the PSLF 2026 updates to your advantage and achieve the financial freedom you deserve as you continue to make a difference in your community.
For the most up-to-date information, always refer to the official Federal Student Aid (FSA) website at studentaid.gov. This resource will provide the definitive details on all PSLF requirements and any future program changes.