Is Your Daily Budget Ready for 2026? A 6-Point Checklist for Financial Confidence
The future, while uncertain, is not entirely unpredictable. When it comes to your finances, proactive planning can make all the difference between feeling overwhelmed and confidently navigating whatever 2026 throws your way. As we inch closer to a new year, economic shifts, evolving market dynamics, and personal life changes can all impact your financial well-being. That’s why now is the perfect time to assess and refine your daily budget to ensure it’s not just surviving, but thriving, in the coming year. This comprehensive guide provides a 6-point checklist designed to empower you with practical solutions and robust strategies for building financial resilience.
Anúncios
Many people view budgeting as a restrictive chore, a necessary evil that limits their spending. However, a well-crafted budget is, in fact, a powerful tool for liberation. It’s a roadmap that helps you allocate your resources intentionally, achieve your financial goals, and ultimately gain greater control over your life. With the right approach, your daily budget can become a source of confidence, not constraint.
In this article, we’ll delve into six critical areas that will help you prepare your budgeting 2026 checklist. From understanding your current financial landscape to strategizing for future growth, each point is designed to offer actionable insights. We’ll discuss how to account for inflation, optimize your spending, build robust emergency funds, and even explore avenues for income diversification. Our goal is to equip you with the knowledge and tools to face 2026 with unwavering financial confidence.
Anúncios
1. Re-evaluate Your Current Financial Snapshot: The Foundation of Your Budgeting 2026 Checklist
Before you can plan for the future, you must have a crystal-clear understanding of your present financial situation. This involves more than just knowing your bank balance; it requires a deep dive into your income, expenses, assets, and liabilities. For your budgeting 2026 checklist, this first step is foundational.
Analyze Your Income Streams
Start by listing all sources of income. Is it solely from your primary job, or do you have freelance work, rental income, or investment dividends? Understand the stability and frequency of each stream. Are any of them likely to change in 2026? Perhaps a promotion is on the horizon, or a side hustle might grow. Documenting these helps you project your total available funds accurately.
Track and Categorize Your Spending
This is often the most revealing part of a financial assessment. For at least 30-60 days, meticulously track every dollar you spend. Use a budgeting app, a spreadsheet, or even a pen and paper. Categorize your expenses into fixed (rent, mortgage, loan payments) and variable (groceries, entertainment, dining out). Pay close attention to discretionary spending – those ‘nice-to-have’ items that often derail budgets. This exercise will highlight exactly where your money is going and reveal potential areas for optimization.
Review Assets and Liabilities
What do you own (assets) and what do you owe (liabilities)? Assets include savings accounts, investments, real estate, and valuable possessions. Liabilities encompass credit card debt, student loans, car loans, and mortgages. Calculate your net worth (assets minus liabilities). A positive and growing net worth is a strong indicator of financial health. Understanding your debt burden, especially high-interest debts, is crucial for prioritizing repayment strategies.
Identify Spending Leaks and Opportunities
Once you have a clear picture of your income and expenses, identify any ‘spending leaks.’ These are often small, recurring expenses that add up over time – unused subscriptions, daily coffee runs, or impulse buys. Conversely, look for opportunities to optimize. Can you negotiate better rates on insurance or internet? Are there cheaper alternatives for certain services? Every dollar saved here is a dollar that can be redirected towards your goals for 2026.
2. Factor in Inflation and Economic Shifts: Adapting Your Daily Budget
Ignoring inflation is like driving with a flat tire – you might get somewhere, but it’s going to be a bumpy and inefficient ride. As we look towards 2026, understanding and anticipating economic shifts, particularly inflation, is paramount for any effective budgeting 2026 checklist.
Understanding Inflation’s Impact
Inflation erodes the purchasing power of your money. What £100 buys today might only buy £95 worth of goods and services next year. This means your current budget might not stretch as far in 2026, even if your income remains the same. Prices for groceries, fuel, utilities, and even services can increase, making your existing budget inadequate unless adjusted.
Research Economic Forecasts
Stay informed about economic predictions for 2026. While no one has a crystal ball, financial institutions and economic analysts often provide forecasts for inflation rates, interest rate changes, and overall economic growth. This information can help you make educated guesses about potential increases in your cost of living. Look for reports from reputable sources like central banks, international monetary funds, and major financial news outlets.
Adjust Key Budget Categories
Based on your research and current trends, proactively adjust categories most susceptible to inflation. For instance, if food prices are projected to rise by 3-5%, increase your grocery budget accordingly. The same applies to transportation, housing costs (if applicable), and utilities. It’s better to slightly overestimate and have a buffer than to underestimate and face a shortfall.
Consider Cost-Saving Alternatives
To combat inflation, explore ways to reduce your expenses without sacrificing quality of life. This could involve meal prepping to save on groceries, carpooling or using public transport to reduce fuel costs, or investing in energy-efficient appliances to lower utility bills. Small changes can cumulatively create significant savings, helping your daily budget absorb inflationary pressures.
3. Build and Bolster Your Emergency Fund: Your Financial Safety Net for 2026
An emergency fund is not just a ‘nice-to-have’; it’s a ‘must-have.’ It acts as a financial safety net, protecting you from unexpected expenses like job loss, medical emergencies, or unforeseen home repairs. For your budgeting 2026 checklist, ensuring this fund is robust is non-negotiable.
Determine Your Target Amount
The traditional advice is to have 3-6 months’ worth of essential living expenses saved. However, for added peace of mind, especially in uncertain economic times, consider aiming for 6-12 months. Essential living expenses include rent/mortgage, utilities, food, transportation, and insurance – basically, what you need to survive if your income suddenly stopped. Calculate this figure precisely.
Automate Your Savings
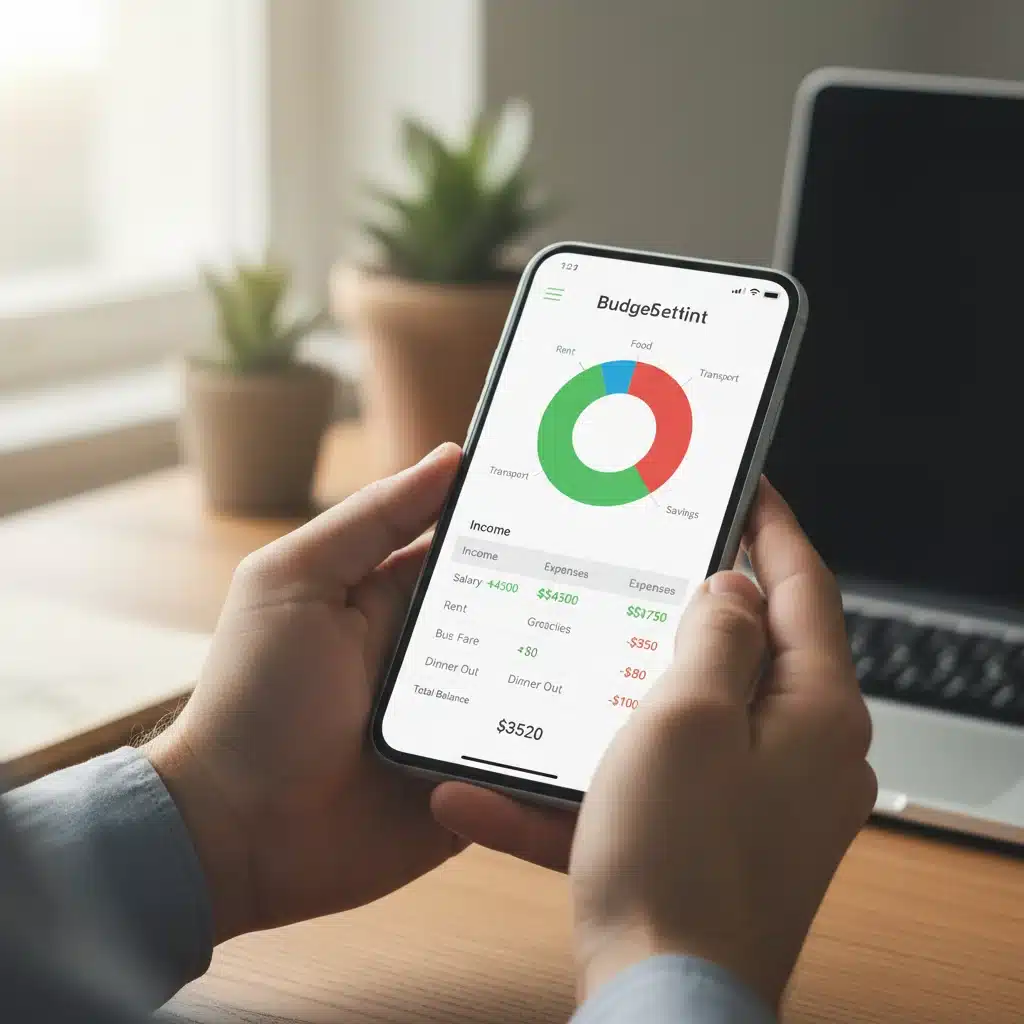
The easiest way to build an emergency fund is to automate contributions. Set up a recurring transfer from your checking account to a separate, high-yield savings account each payday. Treat this transfer like a non-negotiable bill. Out of sight, out of mind, and steadily growing.
Prioritize Debt Repayment (Strategically)
While building an emergency fund, it’s also wise to tackle high-interest debt. Some financial experts suggest building a mini-emergency fund (e.g., £1,000) first, then aggressively paying down high-interest debt, and then returning to fully fund the emergency account. High-interest debt can quickly negate any savings you accumulate, so a balanced approach is often best.
Review and Replenish Regularly
Your emergency fund isn’t a ‘set it and forget it’ item. Life happens. If you tap into it, make it a priority to replenish it as quickly as possible. Also, review your target amount periodically. Has your cost of living increased? Have your responsibilities changed? Adjust your emergency fund goal accordingly to ensure it remains adequate for 2026 and beyond.
4. Optimize Debt Management and Repayment Strategies: Freeing Up Your Daily Budget
Debt can be a heavy burden, stifling your financial progress and limiting your daily budget flexibility. A key component of your budgeting 2026 checklist should be a clear, actionable plan for managing and reducing your debt.
List All Debts and Interest Rates
Start by creating a comprehensive list of all your debts: credit cards, personal loans, student loans, car loans, mortgage, etc. Include the outstanding balance, minimum payment, and, most importantly, the interest rate for each. This overview is crucial for strategizing.
Prioritize High-Interest Debt
The ‘debt snowball’ and ‘debt avalanche’ methods are popular repayment strategies. The debt avalanche method, which prioritizes paying off debts with the highest interest rates first, often saves you the most money in the long run. By eliminating these expensive debts, you free up more cash flow in your daily budget for other goals.
Explore Refinancing and Consolidation Options
If you have multiple high-interest debts, consider options like debt consolidation loans or balance transfer credit cards with 0% introductory APRs. Refinancing a mortgage or student loan might also secure a lower interest rate, reducing your monthly payments and the total interest paid over the life of the loan. Always compare terms and fees carefully before committing.
Automate Payments to Avoid Fees
Missing a payment can lead to late fees and damage your credit score. Set up automatic payments for all your debts to ensure they are paid on time. Even if you’re only making minimum payments, consistency is key. Then, when you have extra funds, make additional principal payments to accelerate your debt-free journey.
5. Explore Income Diversification and Growth Opportunities: Boosting Your 2026 Budget
Relying on a single income source can be risky. For a truly resilient budgeting 2026 checklist, consider ways to diversify and grow your income. This can provide a buffer against unexpected job loss and accelerate your financial goals.
Identify Potential Side Hustles
What skills do you have that could be monetized? Freelancing (writing, graphic design, web development), consulting, tutoring, pet-sitting, driving for ride-share services, or selling crafts online are just a few examples. Even a few hundred extra pounds a month can significantly impact your daily budget and savings capacity.
Invest in Your Skills and Education
Consider taking courses, workshops, or pursuing certifications that can enhance your current career prospects or open doors to new, higher-paying opportunities. Investing in yourself is one of the best ways to increase your earning potential in the long term.
Evaluate Passive Income Streams
While often requiring an initial investment of time or capital, passive income streams can provide ongoing revenue with minimal active effort. Examples include dividend-paying stocks, real estate investments (e.g., rental properties, REITs), creating digital products (e.g., e-books, online courses), or even high-yield savings accounts. Research thoroughly and understand the risks involved before diving in.
Negotiate for Higher Pay or Seek New Opportunities
Don’t be afraid to advocate for yourself. Regularly research salary benchmarks for your role and industry. If you feel underpaid, prepare a strong case for a raise. If a raise isn’t possible, or if you’ve outgrown your current role, actively seek out new job opportunities that offer better compensation and growth prospects for 2026.
6. Set Clear Financial Goals and Review Progress Regularly: Navigating 2026 with Purpose
Without clear goals, your daily budget lacks direction. The final, but arguably most crucial, step in your budgeting 2026 checklist is to define what you want to achieve and establish a system for tracking your progress.
Define SMART Goals
Your financial goals should be SMART: Specific, Measurable, Achievable, Relevant, and Time-bound. Instead of saying, ‘I want to save more,’ try ‘I want to save £5,000 for a down payment on a car by December 2026.’ This clarity makes your goals tangible and easier to work towards.
Short-Term, Mid-Term, and Long-Term Goals
- Short-Term (1 year or less): Building your emergency fund, paying off a credit card, saving for a holiday.
- Mid-Term (1-5 years): Saving for a house down payment, buying a new car, funding a child’s education.
- Long-Term (5+ years): Retirement planning, significant investments, financial independence.
Having a mix of these keeps you motivated and provides a holistic view of your financial journey.
Integrate Goals into Your Daily Budget
Once your goals are defined, allocate specific amounts in your daily budget towards them. Treat savings and investments as non-negotiable expenses, just like your rent or mortgage. This ‘pay yourself first’ approach ensures you’re consistently making progress.
Schedule Regular Reviews
Your budget is a living document, not a static one. Schedule monthly or quarterly reviews to assess your progress. Are you on track to meet your goals? Have your income or expenses changed significantly? Do you need to adjust your budget or your goals? Regular reviews allow you to catch issues early and make necessary course corrections, keeping your budgeting 2026 checklist effective and relevant.
Celebrate Milestones
Financial planning can be a long game, so it’s important to celebrate small victories along the way. Did you pay off a credit card? Did you hit a savings milestone? Acknowledge these achievements. Positive reinforcement can boost your motivation and keep you engaged with your financial journey towards a confident 2026.
Conclusion: Embracing Financial Confidence in 2026
Preparing your daily budget for 2026 isn’t just about crunching numbers; it’s about building a foundation for financial confidence and peace of mind. By systematically working through this 6-point budgeting 2026 checklist, you’re not just reacting to economic changes, but actively shaping your financial future. From a thorough re-evaluation of your current financial snapshot and factoring in the realities of inflation, to bolstering your emergency fund, optimizing debt, exploring new income streams, and setting clear goals, each step is a building block towards greater financial resilience.
Remember, financial planning is an ongoing journey, not a one-time event. The economic landscape is dynamic, and your personal circumstances will evolve. The key to sustained financial health lies in continuous monitoring, adaptation, and a proactive mindset. Make it a habit to regularly review your budget, adjust your strategies as needed, and stay informed about broader economic trends.
By diligently implementing the strategies outlined in this guide, you will transform your daily budget from a source of stress into a powerful tool for achieving your aspirations. Step into 2026 not with apprehension, but with the quiet strength and assurance that comes from being prepared. Your financial future is largely in your hands, and with this checklist, you are well on your way to making it a successful and confident one.
Start today. Take control. And make 2026 your most financially confident year yet.