Navigating the 2026 Dependent Care FSA Changes: What You Need to Know
Anúncios
Understanding and effectively utilizing employee benefits is a cornerstone of sound personal finance, especially for families managing the significant costs associated with dependent care. Among the most valuable of these benefits is the Dependent Care Flexible Spending Account (DCFSA). As we approach 2026, it’s crucial for employees and employers alike to be aware of the impending changes to the 2026 Dependent Care FSA landscape. These adjustments can significantly impact how families plan for and fund their childcare and elder care needs, offering both new opportunities and potential challenges.
The DCFSA allows employees to set aside pre-tax dollars from their paychecks to cover eligible dependent care expenses. This results in substantial tax savings, as the money contributed to a DCFSA is not subject to federal income tax, Social Security, or Medicare taxes. For many working parents and caregivers, this benefit is indispensable, making quality care more affordable and accessible.
Anúncios
However, like many tax-advantaged accounts, the DCFSA is subject to legislative and regulatory updates. The changes anticipated for the 2026 Dependent Care FSA are not merely minor tweaks; they could represent significant shifts in contribution limits, eligibility criteria, and the types of expenses that qualify. Staying informed about these modifications is not just about compliance; it’s about maximizing your financial advantage and ensuring that your family’s care needs are met without undue financial strain.
This comprehensive guide will delve into the specifics of the upcoming 2026 Dependent Care FSA changes. We will explore the historical context of the DCFSA, detail the expected modifications, and provide practical strategies for adapting your financial planning. Our aim is to equip you with the knowledge needed to navigate these changes confidently, ensuring you continue to leverage this powerful benefit to its fullest potential.
Anúncios
The Dependent Care FSA: A Foundation for Family Financial Planning
Before we dive into the specifics of the 2026 Dependent Care FSA changes, let’s briefly review the fundamental principles of the DCFSA. Established to help working individuals and families manage the costs of caring for dependents, the DCFSA offers a powerful tax advantage.
What is a DCFSA?
A Dependent Care Flexible Spending Account (DCFSA) is an employer-sponsored benefit that allows you to contribute pre-tax money from your salary to pay for eligible dependent care expenses. This money is then used to reimburse you for costs incurred for the care of a qualifying individual, typically a child under 13 or an incapacitated spouse or dependent.
How Does it Work?
Employees elect an annual contribution amount, which is then deducted in equal installments from their paychecks throughout the year. These deductions are made before federal income, Social Security, and Medicare taxes are calculated, leading to significant tax savings. When an eligible dependent care expense is incurred, the employee submits a claim for reimbursement from their DCFSA balance.
Key Benefits of a DCFSA
- Tax Savings: The primary benefit is the reduction in taxable income, leading to lower overall tax liability.
- Budgeting Tool: It encourages proactive budgeting for dependent care costs, ensuring funds are available when needed.
- Employer Contribution (Optional): Some employers may choose to contribute to employee DCFSAs, further enhancing the benefit.
The "Use-It-or-Lose-It" Rule
A critical aspect of DCFSAs, similar to Health FSAs, is the "use-it-or-lose-it" rule. Funds not used by the end of the plan year (or a short grace period, if offered by the employer) are typically forfeited. This necessitates careful planning when electing your annual contribution amount.
Anticipated Changes to the 2026 Dependent Care FSA
While specific legislative details are still emerging and can be subject to change, discussions and proposals surrounding the 2026 Dependent Care FSA point towards several key areas of modification. These changes are often driven by economic factors, evolving family structures, and governmental priorities regarding social support and tax policy.
Potential Adjustments to Contribution Limits
One of the most impactful areas of change often relates to contribution limits. Historically, the maximum annual contribution for a DCFSA has been $5,000 per household (or $2,500 for married individuals filing separately). During the COVID-19 pandemic, these limits were temporarily increased for 2021, providing significant relief to families. However, they reverted to the standard amounts thereafter.
For the 2026 Dependent Care FSA, there is speculation about whether these limits will be adjusted. Factors influencing this could include:
- Inflation: The rising cost of living, particularly childcare, often prompts calls for increased contribution limits to maintain the benefit’s real value.
- Economic Conditions: Broader economic trends and governmental fiscal policies can influence decisions regarding tax-advantaged accounts.
- Legislative Priorities: New legislative initiatives aimed at supporting working families or addressing childcare affordability could lead to revised limits.
An increase in the contribution limit would allow families to shield more of their income from taxes, translating into greater savings. Conversely, if limits remain stagnant amidst rising care costs, the relative benefit could diminish.
Revisions to Eligible Expenses
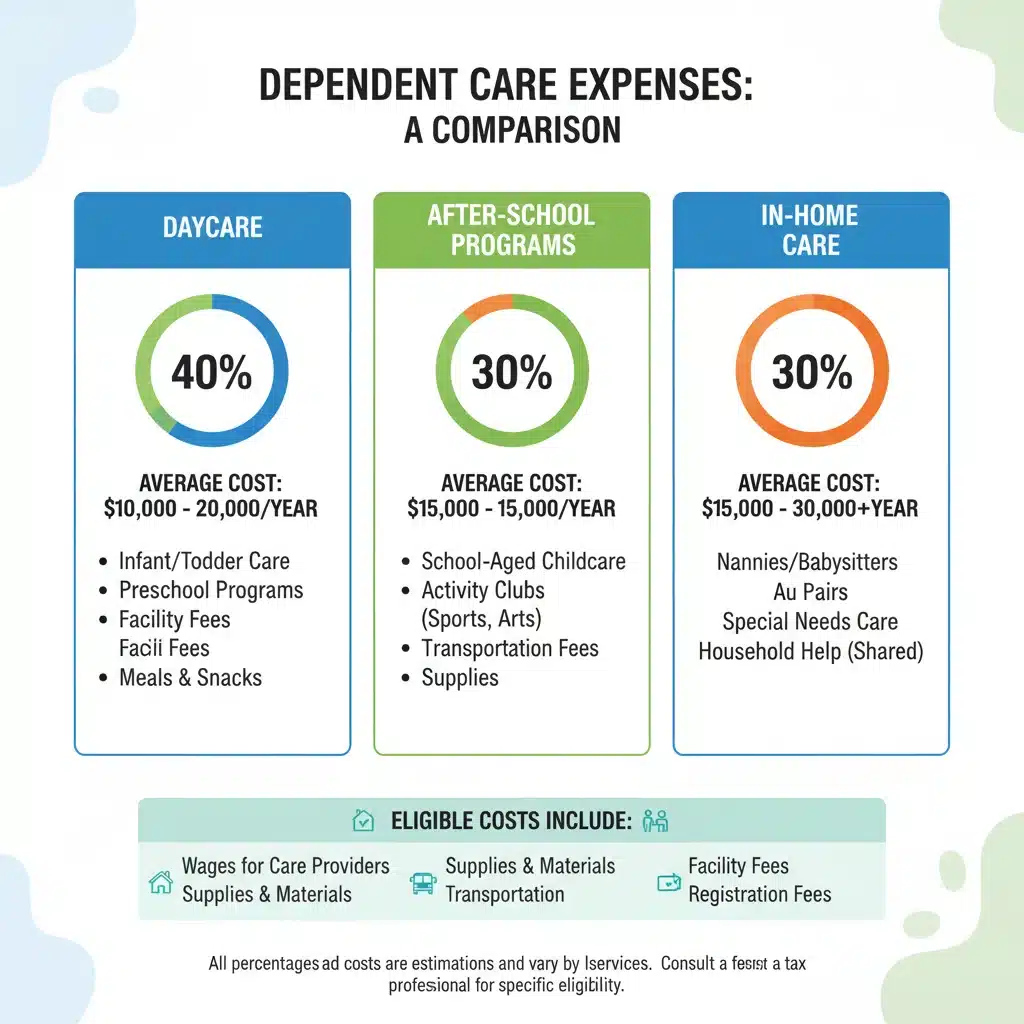
Another area that might see adjustments for the 2026 Dependent Care FSA is the definition of "eligible expenses." Currently, eligible expenses generally include:
- Care in your home (nanny, au pair, babysitter)
- Care outside your home (daycare, preschool, after-school programs)
- Summer day camps (not overnight camps)
- Before and after-school care
- Elder care for a qualifying dependent who lives with you and is physically or mentally unable to care for themselves.
Potential revisions could include:
- Expansion of Qualifying Dependents: There might be discussions about broadening the definition of a qualifying dependent to include a wider range of family members requiring care.
- Inclusion of Educational Services: Currently, tuition for kindergarten and above is generally not eligible. Future changes might explore partial inclusion of certain educational components if they are inseparable from the care provided.
- Technology-Based Care Solutions: With the rise of virtual care and educational platforms, there could be clarifications or expansions to include certain technology-enabled dependent care services.
Changes to Eligibility Requirements
Eligibility for a DCFSA generally requires that both you and your spouse (if married) must be working, looking for work, or a full-time student. The care must be necessary for you (and your spouse) to work or look for work. Any changes to these core requirements for the 2026 Dependent Care FSA could significantly impact who can utilize the benefit.
Possible considerations include:
- Income Thresholds: The introduction or adjustment of income thresholds that might cap eligibility for higher earners, similar to other tax credits.
- Work Requirements: Revisions to what constitutes "working" or "looking for work," potentially accommodating more flexible work arrangements or sabbatical periods.
It is important to reiterate that these are potential changes based on current discussions and historical patterns of benefit adjustments. Employees and employers should monitor official IRS announcements and legislative updates closely as 2026 approaches.
Strategic Planning for the 2026 Dependent Care FSA
Regardless of the specific changes that materialize for the 2026 Dependent Care FSA, proactive planning is essential to maximize your benefits and avoid common pitfalls. Here are some strategies to consider:
1. Stay Informed and Monitor Updates
The most crucial step is to remain updated on official announcements from the IRS and your employer regarding DCFSA rules for 2026. Subscribing to financial news outlets, employer benefit newsletters, and consulting with HR or a financial advisor can help you stay ahead.
2. Accurately Estimate Your Dependent Care Expenses
The "use-it-or-lose-it" rule makes accurate estimation vital. Begin by calculating your anticipated dependent care costs for the entire year. Consider:
- Current Costs: Tally up your regular daycare, after-school care, or in-home care expenses.
- Future Needs: Anticipate any changes, such as a child entering a new age group with different care costs, or planned summer camps.
- Contingencies: While difficult, try to account for unexpected care needs, though remember the "use-it-or-lose-it" rule.
If you’re unsure, it’s often safer to under-contribute slightly than to over-contribute and risk forfeiting funds. However, missing out on significant tax savings by contributing too little is also a consideration.
3. Understand the Interaction with the Child and Dependent Care Tax Credit
It’s important to know that you cannot "double-dip" by using both a DCFSA and the Child and Dependent Care Tax Credit for the same expenses. Generally, you must choose one benefit for a given set of expenses. For most families, especially those in higher tax brackets, the DCFSA often provides greater tax savings due to its pre-tax nature. However, it’s wise to compare the potential benefits of both options based on your specific income and care costs.
4. Review Your Employer’s Plan Details
While federal guidelines set the overarching framework, your employer’s specific DCFSA plan may have unique features, such as a grace period for using funds or a run-out period for submitting claims. Familiarize yourself with these details to ensure you comply with all deadlines and requirements. Your HR department is your best resource for this information.
5. Consider Life Changes
Life events such as marriage, divorce, birth or adoption of a child, or a change in employment status are often considered "qualifying life events." These events may allow you to change your DCFSA election mid-year, even if the 2026 Dependent Care FSA rules generally prohibit mid-year adjustments. Understanding these provisions can provide flexibility when your family’s needs evolve.
Maximizing Your 2026 Dependent Care FSA Benefits
Beyond basic planning, several advanced strategies can help you get the most out of your 2026 Dependent Care FSA.
Coordinate with Your Spouse (if applicable)
If both you and your spouse are employed and eligible for a DCFSA, you must coordinate your contributions. The $5,000 household limit applies regardless of whether one spouse contributes the full amount or both contribute up to $2,500 each. Ensure you don’t collectively exceed this limit to avoid tax complications.
Keep Meticulous Records
Maintain thorough records of all your dependent care expenses, including receipts, invoices from care providers, and payment confirmations. This documentation is crucial for submitting claims for reimbursement and for tax purposes, should you ever be audited. Ensure your care provider provides you with their Taxpayer Identification Number (TIN) or Social Security Number (SSN), as this is required for tax reporting.
Understand Eligible vs. Ineligible Expenses
A common mistake is claiming ineligible expenses. For example, while summer day camps are usually eligible, overnight camps are not. Educational costs for children in kindergarten or higher are generally excluded, as are expenses for care provided by your spouse or a child under age 19. If you are unsure about an expense, consult your plan administrator or IRS Publication 503, "Child and Dependent Care Expenses." Being clear on what qualifies will prevent claim denials and potential tax issues.
The Broader Impact of DCFSA Changes
The modifications to the 2026 Dependent Care FSA will not only affect individual families but can also have broader implications for employers, care providers, and the economy.
For Employers
Employers offering DCFSAs will need to update their benefit administration systems, communicate changes clearly to employees, and ensure compliance with any new regulations. This may involve revising plan documents, updating enrollment materials, and providing training to HR staff. A well-managed DCFSA program can be a significant recruitment and retention tool, demonstrating an employer’s commitment to supporting their workforce’s family needs.
For Care Providers
Changes in DCFSA rules, particularly to eligible expenses or contribution limits, could indirectly impact dependent care providers. For instance, an increase in contribution limits might lead to greater demand for eligible services, while stricter eligibility criteria could reduce the pool of families utilizing the benefit. Care providers should also be aware of the need to provide proper documentation and taxpayer identification numbers to families for reimbursement purposes.
Economic and Social Impact
From a macroeconomic perspective, adjustments to the DCFSA can influence workforce participation, especially among parents and caregivers. Enhanced benefits can incentivize more individuals to remain in or re-enter the workforce, knowing that their care costs are partially offset. Conversely, reductions in benefits could create financial barriers, potentially leading some to reduce work hours or leave the workforce. These changes also reflect evolving societal views on childcare support and family leave policies.
Preparing for Enrollment in the 2026 Dependent Care FSA
As the open enrollment period for 2026 approaches, typically in late 2025, it’s essential to have all your information ready to make an informed decision about your 2026 Dependent Care FSA election.
Key Steps to Take Before Open Enrollment:
- Review Your Current Situation: Assess your family’s current and projected dependent care needs for 2026. Are your children aging out of eligibility? Will they start a new program? Do you anticipate any changes in your work schedule or your spouse’s?
- Gather Cost Estimates: Contact your daycare, after-school program, or other care providers to get their projected rates for 2026. Factor in any potential increases.
- Understand Your Employer’s Offerings: Pay close attention to any communications from your employer regarding their 2026 benefits package, specifically detailing the DCFSA. Look for information on new limits, grace periods, and eligible expenses.
- Consult Resources: Utilize IRS publications (like Publication 503), your employer’s HR department, or a qualified financial advisor to clarify any uncertainties.
- Compare with the Child and Dependent Care Tax Credit: Re-evaluate which tax benefit (DCFSA vs. Tax Credit) offers the greatest advantage for your family given the 2026 rules and your income level.
By taking these preparatory steps, you can ensure that your DCFSA election for 2026 is optimized to provide the maximum tax savings and financial support for your dependent care needs.
Conclusion: Navigating the Future of Dependent Care Benefits
The 2026 Dependent Care FSA changes represent an important moment for families relying on this valuable benefit. While the exact details are still taking shape, the underlying principle remains constant: the DCFSA is a powerful tool for tax-advantaged savings on essential dependent care expenses. By staying informed, meticulously planning, and understanding the nuances of the program, you can continue to leverage the DCFSA to lighten your financial burden and support your family’s well-being.
Remember that the landscape of tax laws and employee benefits is dynamic. What holds true today may shift tomorrow. Therefore, ongoing vigilance and proactive engagement with your employer’s benefits team and official tax resources are paramount. The goal is not just to comply with the new rules but to strategically adapt your financial approach to ensure your family continues to thrive amidst evolving economic and legislative environments.
Embrace the opportunity to review your financial planning, educate yourself on the upcoming changes, and make the most informed decisions for your dependent care needs in 2026 and beyond. Your diligence now will pay dividends in future tax savings and peace of mind.
Author