2026 Medicare Part D Shake-Up: Understanding Your Prescription Costs
Anúncios
The landscape of prescription drug coverage for millions of Americans is on the cusp of a monumental shift. As we approach 2026, significant reforms to Medicare Part D, primarily driven by the Inflation Reduction Act (IRA), are set to redefine how beneficiaries manage their medication costs. For many, this will translate into substantial savings and greater predictability, while for others, it necessitates a thorough understanding of the new rules to optimize their benefits. This comprehensive guide will delve deep into the upcoming Medicare Part D 2026 changes, helping you navigate the complexities and prepare for what’s ahead.
Anúncios
The Genesis of Change: The Inflation Reduction Act (IRA)
The Inflation Reduction Act, signed into law in August 2022, is a landmark piece of legislation that includes several provisions aimed at lowering healthcare costs for seniors. While some aspects of the IRA, such as the $35 cap on insulin costs and free vaccines under Part D, have already taken effect, the most impactful changes to Medicare Part D 2026 are still on the horizon. These reforms are designed to address long-standing concerns about the escalating price of prescription drugs and the financial burden placed on beneficiaries, particularly those with high medication needs.
Key Provisions of the IRA Affecting Medicare Part D
- Out-of-Pocket Cap: This is arguably the most significant change. Starting in 2025, a $2,000 annual cap on out-of-pocket prescription drug costs will be implemented. This means that once a beneficiary spends $2,000 out of their own pocket in a calendar year, they will not pay any more for covered Part D drugs for the remainder of that year. This is a game-changer, especially for individuals with chronic conditions requiring expensive medications.
- Elimination of 5% Coinsurance in Catastrophic Phase: Currently, once beneficiaries reach the catastrophic phase of Part D coverage, they are still responsible for 5% of their drug costs. The IRA eliminates this coinsurance, meaning that after reaching the out-of-pocket cap, beneficiaries will pay nothing for covered Part D drugs. This provision takes full effect in 2025, paving the way for the simplified structure in 2026.
- Manufacturer Discounts and Rebates: The IRA empowers Medicare to negotiate drug prices for certain high-cost medications, starting with a limited number of drugs in 2026 and expanding in subsequent years. This negotiation power is expected to drive down drug costs for both Medicare and beneficiaries.
- Premium Stabilization: While not directly an out-of-pocket cost, the IRA includes provisions to slow the growth of Part D premiums, aiming to make coverage more affordable and predictable over time.
Understanding the New Medicare Part D Structure in 2026
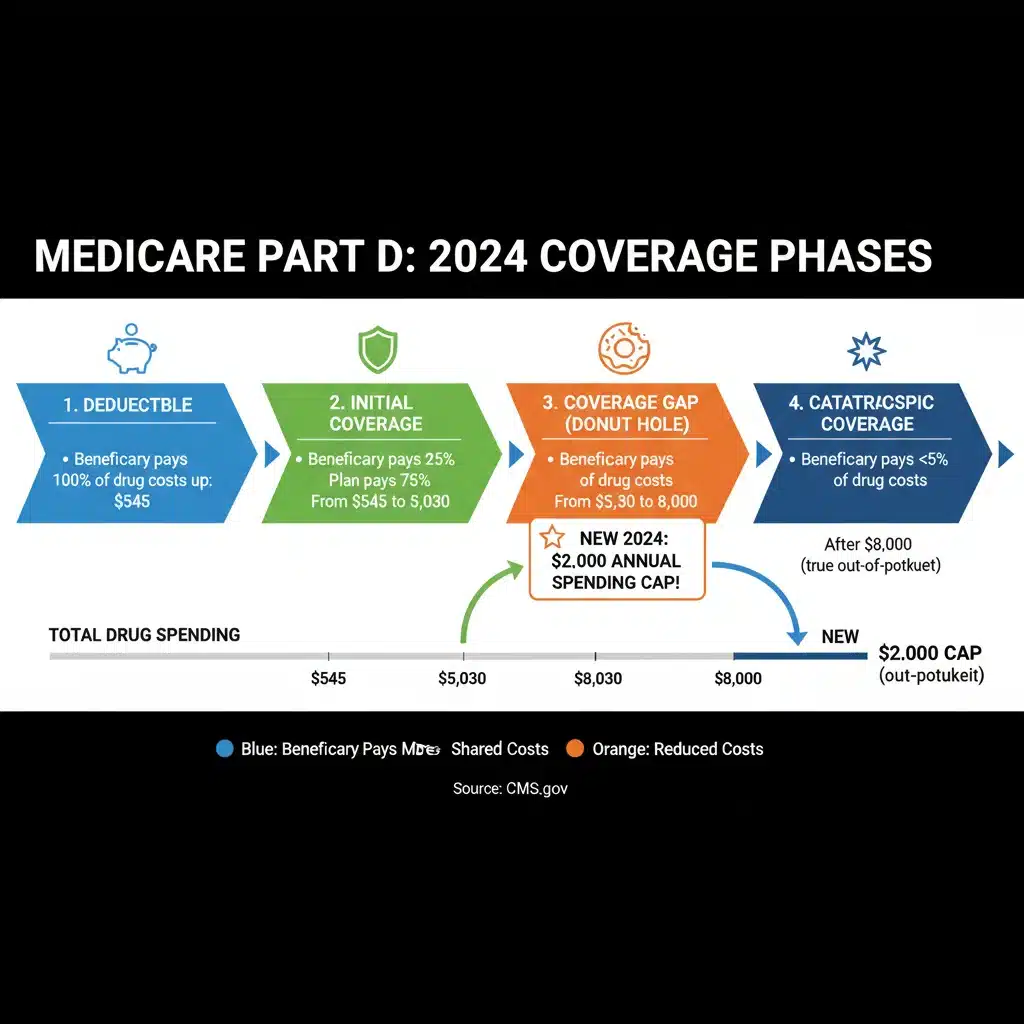
To fully grasp the implications of the Medicare Part D 2026 changes, it’s essential to understand how the current Part D structure works and how it will evolve. Currently, Part D has several phases:
Anúncios
- Deductible: You pay the full cost of your drugs until you meet your plan’s deductible.
- Initial Coverage Phase: After meeting the deductible, you pay a copayment or coinsurance, and your plan pays the rest, until your total drug costs (what you and your plan have paid) reach a certain limit.
- Coverage Gap (Donut Hole): Once you hit the initial coverage limit, you enter the “donut hole,” where you pay a higher percentage of your drug costs (currently 25% for brand-name and generic drugs) until you reach the catastrophic coverage threshold.
- Catastrophic Coverage: After reaching the catastrophic threshold, you pay a small coinsurance (currently 5%) for your remaining drug costs.
In 2026, this structure will be significantly streamlined and made more consumer-friendly, primarily due to the introduction of the out-of-pocket cap. The most notable change is the effective elimination of the catastrophic phase’s 5% coinsurance for beneficiaries once they hit the new $2,000 out-of-pocket maximum. This means that for beneficiaries, once they spend $2,000 out of pocket, their costs for covered Part D drugs will drop to zero for the rest of the year.
The $2,000 Out-of-Pocket Cap: A Deeper Dive
The $2,000 annual out-of-pocket cap for Medicare Part D 2026 is a monumental change that will provide unprecedented financial protection for beneficiaries. This cap includes costs that count towards your true out-of-pocket (TrOOP) spending, which encompasses your deductible, copayments, coinsurance, and the discount you receive on brand-name drugs in the coverage gap. It’s important to clarify what this cap means in practice:
- Predictability: For the first time, beneficiaries will have a clear upper limit on their annual drug expenses, allowing for better financial planning and budgeting.
- Relief for High-Cost Users: Individuals with chronic conditions, rare diseases, or those requiring expensive specialty medications will experience the most significant relief. Previously, the 5% coinsurance in the catastrophic phase could still amount to thousands of dollars for those with very high drug costs.
- Impact on the Coverage Gap: While the coverage gap itself isn’t eliminated, the out-of-pocket cap significantly mitigates its impact. Many beneficiaries with high drug costs will hit the $2,000 cap while still in or shortly after exiting the coverage gap, effectively limiting their exposure to higher costs.
Who Benefits Most from the 2026 Medicare Part D Changes?
While all Part D beneficiaries stand to benefit from more stable premiums and potential drug price negotiations, certain groups will see the most direct and substantial financial relief:
- Individuals with high annual prescription drug costs: This includes those managing multiple chronic conditions like diabetes, heart disease, or autoimmune disorders, who often rely on several expensive medications.
- Beneficiaries taking specialty drugs: These medications, often used to treat complex or rare conditions, can cost thousands of dollars per month. The $2,000 cap provides a crucial safety net.
- Low-income individuals receiving Extra Help: While Extra Help already provides significant assistance, the changes further reduce the financial burden, ensuring even greater access to necessary medications without prohibitive costs.
Preparing for Medicare Part D 2026: What You Need to Do Now
Even though 2026 might seem a long way off, proactive planning can help you maximize your benefits and minimize potential disruptions. Here’s how you can prepare:
1. Review Your Current Part D Plan Annually
Even before 2026, it’s crucial to review your Part D plan during the Annual Enrollment Period (AEP), which runs from October 15th to December 7th each year. Plans can change their formularies (list of covered drugs), costs, and preferred pharmacies annually. What was the best plan for you this year might not be next year.
- Check your medications: Ensure all your current prescriptions are covered by your chosen plan’s formulary for the upcoming year.
- Compare costs: Look at deductibles, copayments, and coinsurance for your specific drugs across different plans.
- Consider pharmacy networks: Verify that your preferred pharmacies are in the plan’s network to avoid higher out-of-network costs.
2. Understand the Out-of-Pocket Cap’s Implications for Your Budget
Once the $2,000 cap is in place for Medicare Part D 2026, you can budget with greater certainty. If you anticipate high drug costs, knowing your maximum annual expenditure can significantly reduce financial stress. Start thinking about how this cap might impact your personal healthcare budget and savings goals.
3. Explore Extra Help (Low-Income Subsidy – LIS)
If you have limited income and resources, you might qualify for Extra Help, a Medicare program that helps pay for Part D prescription drug costs. This program can significantly reduce your premiums, deductibles, and copayments. The IRA has also made improvements to Extra Help, expanding eligibility for full benefits starting in 2024. Even if you didn’t qualify before, it’s worth re-evaluating your eligibility.
4. Stay Informed About Drug Price Negotiations
The ability for Medicare to negotiate drug prices is a new and evolving aspect of the IRA. While the initial list of drugs subject to negotiation will be limited, it’s a critical step towards reining in pharmaceutical costs. Keep an eye on announcements from the Centers for Medicare & Medicaid Services (CMS) regarding which drugs will be negotiated and how this might impact your specific medications.
5. Utilize Medicare Resources and Tools
Medicare.gov is an invaluable resource for comparing Part D plans. The Plan Finder tool allows you to enter your medications and preferred pharmacies to see estimated costs for different plans. As 2026 approaches, this tool will be updated to reflect the new out-of-pocket cap and other changes, making it even more essential for informed decision-making.
Potential Challenges and Considerations
While the Medicare Part D 2026 changes are largely beneficial, it’s also important to consider potential challenges or areas that may require careful attention:
- Plan Adjustments: Part D plans may adjust their formularies, deductibles, or premiums in response to the new regulations. While the IRA aims to stabilize premiums, plans will still have flexibility in how they structure their benefits to remain competitive.
- Drug List Changes: As Medicare negotiates drug prices, there might be shifts in which drugs are preferred or covered by certain plans. Staying updated on your plan’s formulary is crucial.
- Understanding Your Costs: Even with the cap, understanding how your costs accumulate towards the $2,000 limit will be important. Not all spending counts towards the out-of-pocket maximum, only costs for covered Part D drugs. For instance, drugs not on your plan’s formulary or those purchased out-of-network might not count.
- Initial Out-of-Pocket Spending: While the cap provides long-term relief, beneficiaries will still be responsible for their deductible and initial coverage phase costs until they reach the $2,000 threshold. For those on tight budgets, managing these upfront costs will still be a consideration.
The Broader Impact of the Inflation Reduction Act on Seniors
Beyond Medicare Part D 2026, the Inflation Reduction Act brings other significant changes that will benefit seniors:
- Insulin Cost Cap: As of 2023, monthly out-of-pocket costs for insulin are capped at $35 for Medicare beneficiaries. This has already provided immense relief for millions living with diabetes.
- Free Vaccines: All adult vaccines recommended by the Advisory Committee on Immunization Practices (ACIP) are now free for Medicare Part D beneficiaries, including shingles and Tdap vaccines. This removes a significant financial barrier to preventive care.
- Medicare Drug Price Negotiation: Starting in 2026, Medicare will begin negotiating prices for a select number of high-cost drugs, with more added over time. This is a historic step that could fundamentally alter the pharmaceutical market and lead to lower overall drug costs.
These provisions collectively represent a comprehensive effort to make healthcare more affordable and accessible for older Americans, with the Medicare Part D 2026 reforms being a cornerstone of this initiative.
Case Studies: How the $2,000 Cap Will Help
To illustrate the profound impact of the Medicare Part D 2026 out-of-pocket cap, let’s consider a few hypothetical scenarios:
Scenario 1: The Chronic Condition Patient
Maria, 70, has multiple chronic conditions requiring several brand-name medications. Currently, her annual drug costs are around $15,000. Under the current Part D structure, after reaching the catastrophic phase, she still pays 5% of her remaining drug costs. This 5% can easily amount to hundreds or even thousands of dollars each year, creating significant financial strain.
With the Medicare Part D 2026 changes, Maria’s out-of-pocket spending would be capped at $2,000. Once she reaches this threshold, she would pay nothing more for her covered medications for the rest of the year. This provides her with predictable costs and substantial annual savings, allowing her to better manage her fixed income.
Scenario 2: The Specialty Drug User
John, 75, takes a specialty medication for a rare autoimmune disease that costs $10,000 per month. Under the current system, even after reaching the catastrophic phase, his 5% coinsurance means he could still be paying $500 per month for this one drug, totaling $6,000 annually just for the catastrophic portion, in addition to his deductible and initial coverage phase costs.
In Medicare Part D 2026, John’s maximum out-of-pocket for all covered drugs would be $2,000. This means that after spending $2,000, he would pay nothing for his $10,000/month medication for the remainder of the year. This change transforms his financial outlook, making a life-sustaining medication truly affordable.
Scenario 3: The Unexpected Illness
Sarah, 68, is generally healthy and typically has low prescription drug costs, staying well within her initial coverage phase. However, in 2026, she is diagnosed with cancer and requires expensive chemotherapy drugs. Without the cap, her costs could quickly skyrocket into the tens of thousands of dollars, leaving her with significant financial responsibility even in the catastrophic phase.
Thanks to the Medicare Part D 2026 cap, Sarah would have peace of mind knowing that her out-of-pocket drug expenses would not exceed $2,000, regardless of how expensive her treatments become. This provides a critical financial safety net during a challenging time.
Advocacy and Future Outlook
The reforms in the Inflation Reduction Act are a direct result of years of advocacy by consumer groups, patient organizations, and lawmakers pushing for lower drug costs. While these changes are significant, the conversation around prescription drug affordability is ongoing.
Future legislative efforts may continue to build upon these reforms, potentially expanding the number of drugs subject to negotiation, further refining the Part D benefit structure, or addressing other aspects of drug pricing. Staying engaged and informed about these developments will be important for all Medicare beneficiaries.
Conclusion: A New Era for Medicare Part D
The upcoming changes to Medicare Part D 2026, particularly the implementation of the $2,000 out-of-pocket cap, mark a new era for prescription drug coverage. These reforms are designed to offer greater financial protection, predictability, and affordability for millions of seniors and individuals with disabilities.
While the benefits are clear, understanding the nuances of these changes and actively planning for them is paramount. By reviewing your current plan, utilizing Medicare resources, and staying informed, you can ensure you are well-prepared to take full advantage of the improved Medicare Part D 2026 benefits. This shift represents a significant step forward in making essential medications accessible and affordable for those who need them most.
Author